Helpful Resources for Seniors
Helpful Resources for Seniors Navigate life's next chapter with confidence
  • Home
  • Lifestyle
  • Well-Being
  • Finance

How to Pass Down Wealth Without Family Conflicts

September 8, 2025 · Finance

Close-up of a senior's hands writing a letter with a fountain pen, with reading glasses nearby, lit by a soft evening desk lamp.

Actionable Strategies for a Smooth Inheritance Process

A successful estate plan is not created in a vacuum. It requires thoughtful consideration and a series of concrete actions. The following strategies are the building blocks of a plan that can be passed down with clarity and fairness, minimizing the potential for conflict.
An older mother, late 70s, holding hands with her adult daughter, 50s, while her adult son, 50s, listens intently during a family conversation in a li
Open conversations help families understand important decisions together.

1. Communicate Your Intentions Openly and Early

This is arguably the most important step and the one most often overlooked. Many family conflicts arise not from the decisions themselves, but from the surprises and misunderstandings they create. Holding a family meeting or having individual conversations with your children can demystify the process. You do not need to disclose exact dollar amounts, but you should explain the why behind your plan. For example, if you are giving one child a larger share because they have greater financial needs or served as your primary caregiver, explaining your reasoning can prevent the other children from feeling unloved or undervalued.
Older couple, late 60s, seated with a female attorney, mid-40s, around a desk reviewing legal documents in a sunny office.
Planning for the future with expert guidance brings peace of mind.

2. Create a Comprehensive, Legally Sound Estate Plan

Your plan should be more than just a will. A complete plan typically includes:

  • A Will: To direct the distribution of assets that are in your name alone and to name an executor.
  • A Revocable Living Trust: To hold major assets like your home and brokerage accounts, allowing them to pass to heirs without going through probate.
  • Durable Power of Attorney: This appoints someone to manage your financial affairs if you become incapacitated and unable to do so yourself.
  • Healthcare Power of Attorney (or Healthcare Proxy): This appoints someone to make medical decisions for you if you cannot.
  • A Living Will: This document outlines your wishes for end-of-life medical care.

Working with an experienced estate planning attorney is essential to ensure these documents are drafted correctly according to your state’s laws and that they accurately reflect your wishes.
An older woman in a blue blazer sits at a desk, thoughtfully consulting with a professional female attorney about documents.
Carefully discussing important decisions with a trusted advisor.

3. Choose Your Executor or Trustee Wisely

The person in this role must be trustworthy, organized, responsible, and a good communicator. While it is common to name an adult child, consider the family dynamics. If your children do not get along, appointing one as the executor over the others could ignite sibling rivalries. In such cases, it may be better to name a neutral third party, such as a trusted friend, an attorney, or a corporate trustee (like a bank). This removes the family member from the difficult position of having to say “no” to their siblings.
Older woman and adult daughter at a kitchen table, looking at a framed photo of their family home and legal documents.
Discussing how to handle the cherished family home for future generations.

4. Plan for the Division of “Indivisible” Assets

It is easy to divide a bank account. It is much harder to divide a family home, a vacation cabin, or a small business. These assets often carry deep sentimental value and can become major points of contention. Consider your options ahead of time:

  • Sell and Divide: The simplest approach is often to direct that the asset be sold and the cash proceeds divided equally among the heirs.
  • Buyout Option: You can include instructions allowing one heir to buy out the others’ shares of the property, perhaps based on an official appraisal.
  • Equalize with Other Assets: If one child wants the family home, you can give it to them while giving other children assets of equivalent value from your investment portfolio or life insurance. For example, if the home is worth $300,000 and you have two children, one can get the home and the other can receive $300,000 from your other accounts.
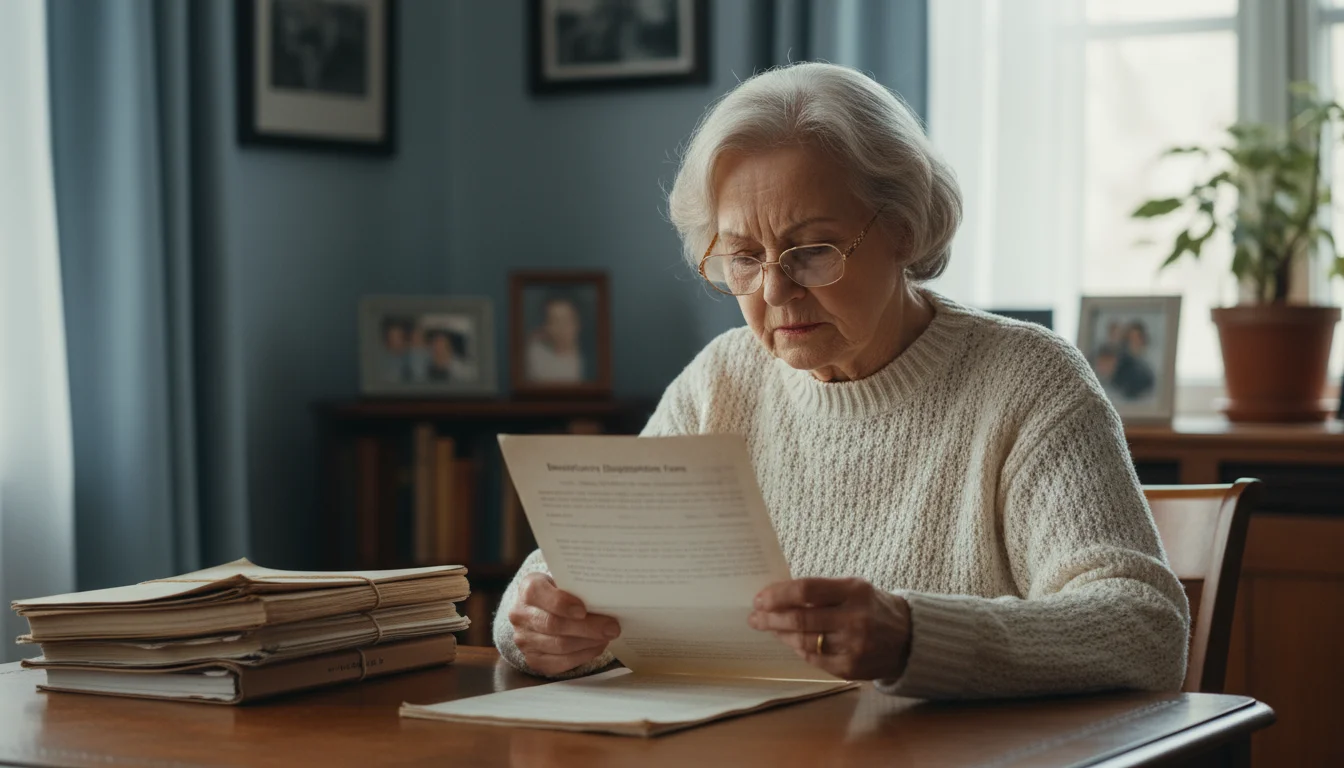
Older woman, late 70s, wearing glasses, intently reviews a faded beneficiary form at a wooden desk, with other documents nearby.
Reviewing old forms for important details can uncover forgotten financial plans.

5. Double-Check Your Beneficiary Designations

This is a critical and often-missed step. Assets like 401(k)s, IRAs, life insurance policies, and annuities pass directly to the person named as the beneficiary on the account paperwork. These designations override your will. If your will says your estate should be split equally between your three children, but your old 401(k) from a previous job only lists your eldest child as the beneficiary, that child gets the entire account. It is vital to review your beneficiary forms every few years and after major life events like a divorce or death.
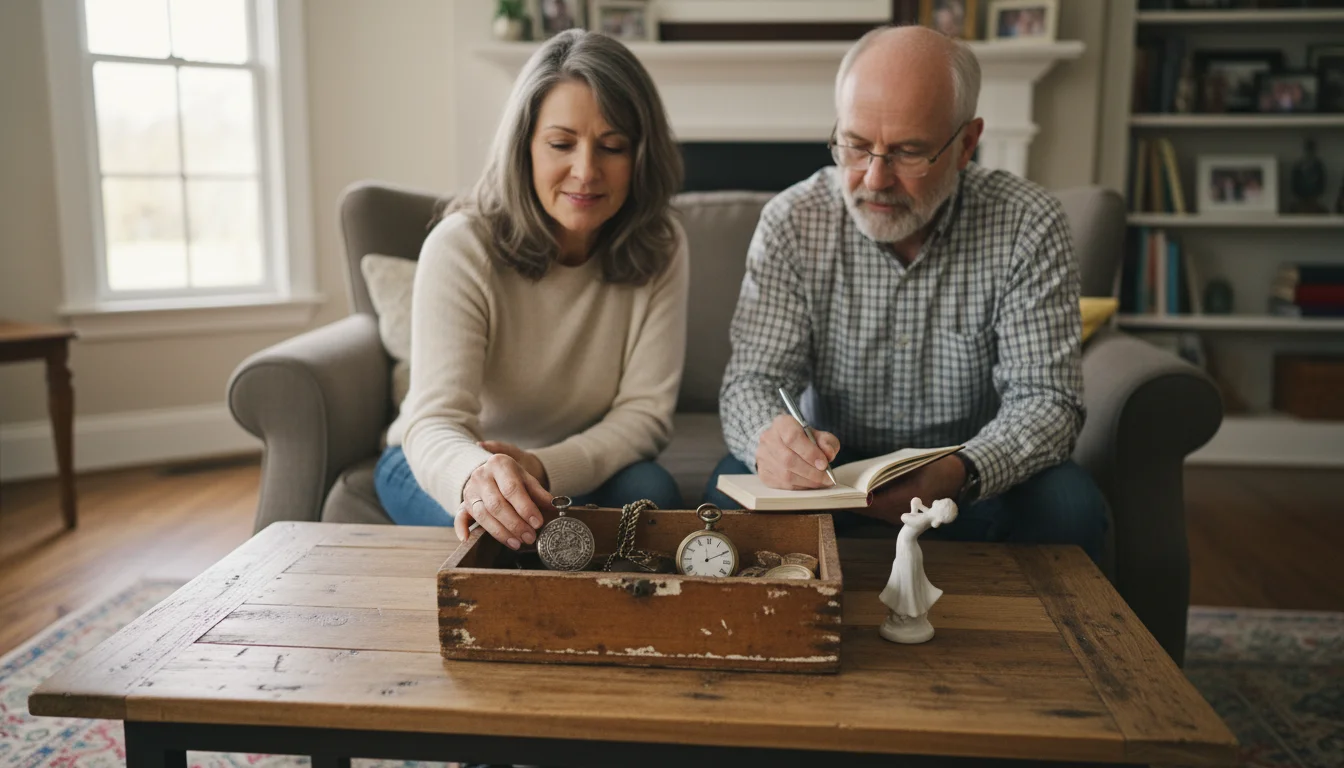
Two adult siblings, a man and a woman, look at sentimental items like a locket and watch in a wooden box on a coffee table, a notebook nearby.
Talking through memories and plans for cherished family treasures.

6. Address Sentimental Personal Property Separately

Sometimes the most bitter family fights are not over money, but over items with little monetary value, like mom’s wedding ring, dad’s old watch, or a favorite piece of furniture. You can prevent these disputes by creating a “personal property memorandum.” This is a signed letter that is referenced in your will, detailing who should receive specific sentimental items. Alternatively, you can suggest a fair method for division in your will, such as having your children take turns choosing items.
An older woman in a sunlit study, wearing reading glasses, reviews legal documents on a large wooden desk. A sticky note marks one document, and a fam
Staying on top of your plans as life changes is a smart move.

7. Review and Update Your Plan Regularly

An estate plan is not a “set it and forget it” document. Your life, your family, and financial laws can change. Plan to review your documents with your attorney every three to five years, or after any major life event such as a birth, death, marriage, or divorce in the family. An outdated plan can be just as problematic as no plan at all.

For official information on Social Security and Medicare, visit SSA.gov and Medicare.gov. Federal tax information is at the IRS.

Pages: 1 2 3 4 5 6

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • Grandfather kneeling in a sunlit hallway adjusts the backpack straps of a young girl holding a water bottle. 8 Social Security Rules Grandparents Raising Grandkids Should Know
  • Smiling older woman holding a script in front of a studio microphone with headphones around her neck. 9 Part-Time Jobs That Pay Retirees Over $25 an Hour
  • Stylized illustration of elderly people walking with canes and walkers through colorful arches toward a medical building. 7 Medicare Programs for Low-Income Retirees
  • Illustration of a celestial compass with an arch labeled DEC 31 transitioning from autumn leaves to a snowy winter landscape. 8 Year-End Moves That Could Lower Your 2026 Tax Bill
  • Vintage illustration of the US Capitol dome framed by circular stripes reading SECURE 3.0 and 2027 above a rolled document. 9 Things the Next Congress Could Do on Retirement Savings
  • Smiling senior man harvesting red apples into a wooden basket on a ladder in a sunlit orchard. Top 20 Social-Security Questions and Answers
  • Older couple unloads cardboard moving boxes and folding lawn chairs from the back of an estate wagon outside a sunny house. 7 Retirement Myths About Moving to Florida
  • Coastal beach houses above water with chained underwater boulders labeled mortgage, property taxes, and maintenance. 7 Costs That Surprise Retirees Who Move to a Beach Town
  • Illustration of an older woman standing at a crossroads looking at a signpost pointing to Part A, Part B, Medigap, and Part D. 8 Medicare Terms Retirees Constantly Confuse
  • Older couple hiking on a coastal trail overlooking rocky cliffs, crashing ocean waves, and forested mountains. 12 Retirement Places Within an Hour of Both Mountains and Ocean

Newsletter

Get the latest posts delivered to your inbox.

Related Articles

An older woman with gray hair smiling as she reviews utility bills and paperwork at a wooden table.

The Overlooked Benefit for Seniors Living Alone

Discover vital benefits for seniors living alone, including Medicare savings, food aid deductions, and utility…

Read More →
An older woman smiles holding her smartphone next to a notepad on a sunlit kitchen table, feeling empowered.

The Telephone Consumer Protection Programs That Pay Seniors to Report Scam Calls

Learn how federal consumer protection programs allow seniors to claim $500 to $1,500 per illegal…

Read More →
A smiling senior woman sits at her desk in a bright home office, looking happy and in control of her finances.

How to Choose Between Annuities and Investments

Table of Contents Introduction: Taking Control of Your Finances in Retirement Understanding the Financial Basics…

Read More →
A woman sits at a wooden dining table reviewing a printed Social Security earnings record with a pencil in hand.

9 Signs Your Social Security Statement Has an Error

Discover 9 critical signs your Social Security statement has an error and learn the exact…

Read More →
A small, house-shaped piggy bank sitting next to a single key on a wooden table in soft, natural light.

How to Navigate Housing Assistance Programs for Seniors

Table of Contents Introduction: Taking Control of Your Finances in Retirement Understanding the Financial Basics…

Read More →
tax myths

6 Tax Myths That Could Cost You – Busted!

Navigating tax forms can be tricky. Don’t let myths cost you! Stop believing these tax…

Read More →
Illustration of a celestial compass with an arch labeled DEC 31 transitioning from autumn leaves to a snowy winter landscape.

8 Year-End Moves That Could Lower Your 2026 Tax Bill

Discover 8 practical year-end tax moves for seniors to lower your 2026 tax bill, claim…

Read More →
Senior man wearing glasses and a sweater sits at a wooden table reviewing paperwork beside a calculator and a coffee mug.

Average Social Security Benefit for Men: How Does Your Payment Compare?

Discover how the average Social Security benefit for men compares to national benchmarks, how claiming…

Read More →
A home office desk in daylight, with a financial planner, glasses, and a framed photograph of a happy older person.

How to Spot Investment Scams Targeting Seniors

Actionable Strategies and Money-Saving Tips Knowledge is your shield, and a set of practical habits…

Read More →
Helpful Resources for Seniors Helpful Resources for Seniors

Navigate life's next chapter with confidence

Inedit Agency S.R.L.
Bucharest, Romania

contact@helpfulresourcesforseniors.com

Explore

  • Home
  • About Us
  • Editorial Policy
  • Privacy Policy
  • Terms and Conditions
  • Subscribe
  • Unsubscribe
  • Contact
  • Request to Know
  • Request to Delete
  • CA Private Policy

Categories

  • Finance
  • Lifestyle
  • Well-Being

© 2026 Helpful Resources for Seniors. All rights reserved.