Entering your 60s is often envisioned as a time to slow down, enjoy the fruits of your labor, and prepare for a relaxing retirement. However, for a growing number of seniors, this decade is shadowed by the stress of carrying debt. Whether it’s a mortgage, credit card balances, or medical bills, debt can feel like a heavy weight, especially when you’re on a fixed or reduced income. The good news is that achieving financial freedom after 60 is not just a dream—it is an achievable goal. With a clear plan and a dose of determination, you can take control of your finances and work toward a debt-free retirement.
This guide is designed to provide you with a practical, step-by-step roadmap for senior debt reduction. We will break down complex topics into simple terms and give you the tools you need to build a secure financial future.
This article is for informational purposes only and is not intended to be financial advice. Please consult with a qualified financial professional for advice tailored to your individual situation.
The First Step: Get a Clear Picture of Your Debt
You cannot fight an enemy you cannot see. The first, most crucial step in any debt payoff plan is to understand exactly what you owe, who you owe it to, and how much it’s costing you. This process can feel intimidating, but facing the numbers head-on is the only way to build an effective strategy.
Why this is important: Gaining clarity eliminates guesswork and anxiety. It transforms a vague, stressful feeling of “being in debt” into a concrete list of problems that you can solve one by one. This is the foundation of all successful retirement debt strategies.
How to do it:
- The name of the creditor (e.g., Chase Bank, Ford Motor Credit).
- The total balance you currently owe.
- The interest rate, also known as the Annual Percentage Rate (APR). This is one of the most important numbers.
- The minimum monthly payment required.
Once you have this master list, you have a powerful tool. You can now see your entire financial picture in one place and are ready to create a plan of attack.
Create a Realistic Retirement Budget
A budget isn’t about punishment or depriving yourself of everything you enjoy. It’s about empowerment. A budget is simply a plan that tells your money where to go, rather than wondering where it went. For seniors on a fixed income, a budget is the key to unlocking extra cash to accelerate debt payoff.
Why this is important: Without a budget, it’s nearly impossible to know how much extra money you can realistically put toward your debt each month. A clear budget reveals your spending habits and identifies areas where you can make small changes that have a big impact over time.
How to do it:
- Calculate Your Total Monthly Income: Add up all sources of income you receive each month. This includes Social Security benefits, pension payments, any part-time work wages, and planned withdrawals from retirement accounts like a 401(k) or IRA. This gives you your total monthly income.
- Track Your Expenses: For at least one full month, track every single dollar you spend. You can use a notebook, a simple app on your phone, or your bank statements. Group your spending into categories like:
- Fixed Needs: Housing (mortgage/rent), utilities, insurance, property taxes, minimum debt payments.
- Variable Needs: Groceries, gasoline, healthcare costs (prescriptions, co-pays).
- Wants: Dining out, hobbies, entertainment, gifts, travel.
- Analyze and Find Your Surplus: Subtract your total monthly expenses from your total monthly income. If you have money left over, that’s your starting point for extra debt payments. If you’re breaking even or spending more than you earn, look closely at the “Wants” category. Identify one or two areas where you can cut back temporarily to free up cash. Even finding an extra $50 or $100 per month can make a significant difference.
Choose Your Debt Payoff Strategy
Now that you know what you owe and how much extra money you can find each month, it’s time to choose a structured approach. Having a method keeps you motivated and ensures your extra payments are having the maximum possible impact. Two of the most popular and effective senior debt reduction methods are the Debt Avalanche and the Debt Snowball.
Strategy 1: The Debt Avalanche
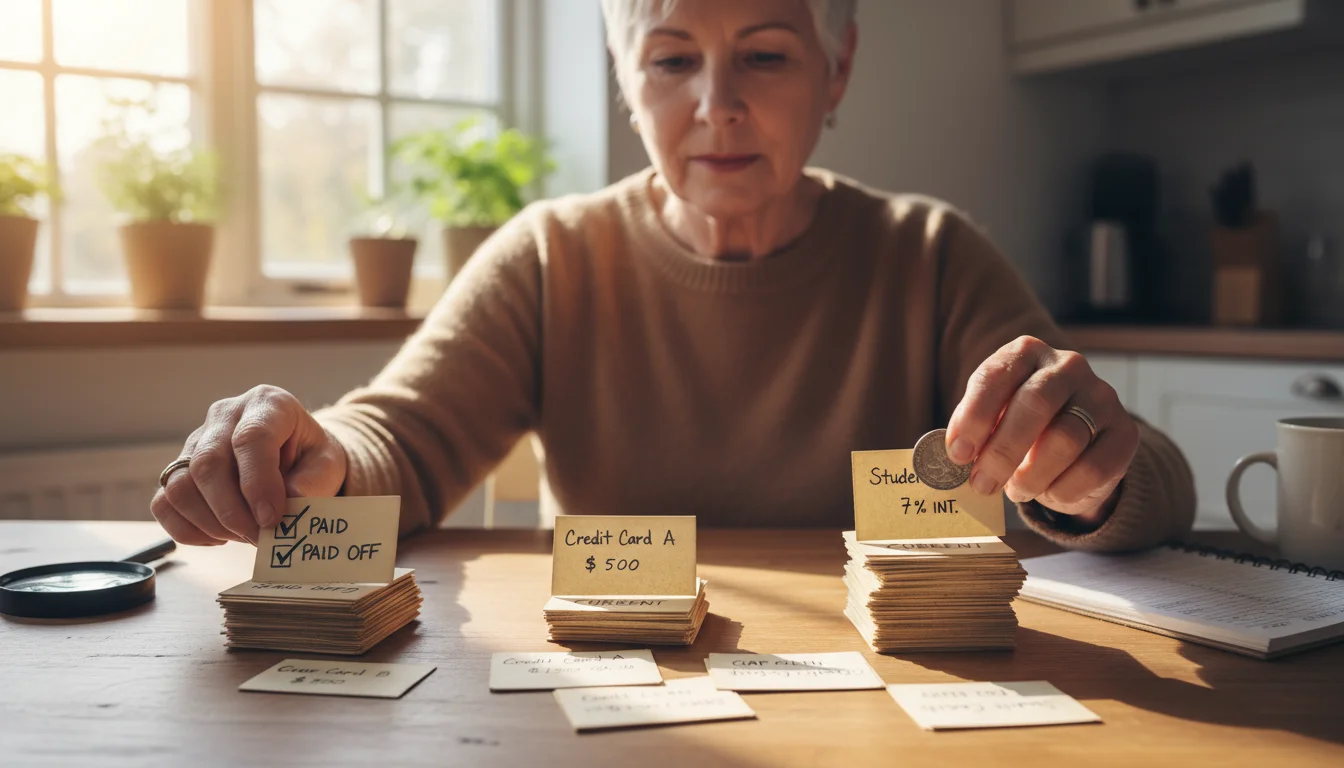
The Debt Avalanche method is the most efficient from a mathematical standpoint.
Why it works: By focusing on your highest-interest debt first, you reduce the total amount of interest you pay over the life of your loans. This means you save the most money and get out of debt faster, which is a primary goal for any senior working with a limited income.
How to do it:
- Organize your debt list from the highest interest rate (APR) to the lowest.
- Continue to make the minimum payments on all your debts.
- Take all the extra money you found in your budget and apply it to the debt with the highest interest rate.
- Once that debt is completely paid off, take the entire amount you were paying on it (the minimum payment plus the extra) and “roll” it over to the debt with the next-highest interest rate.
- Repeat this process until you are completely debt-free.
Strategy 2: The Debt Snowball
The Debt Snowball method focuses on behavior and motivation.
Why it works: Paying off your smallest debt first gives you a quick, tangible victory. This psychological boost can provide powerful motivation to keep going. Seeing an entire account disappear can feel more rewarding than slowly chipping away at a large, high-interest balance.
How to do it:
- Organize your debt list from the smallest total balance to the largest, regardless of the interest rate.
- Continue to make the minimum payments on all your debts.
- Take all your extra money and apply it to the debt with the smallest balance.
- Once that debt is paid off, celebrate your win! Then, take the entire amount you were paying on it and apply it to the debt with the next-smallest balance.
- As you pay off each debt, your “snowball” of payment money grows, knocking out the next debts even faster.
Which one is right for you? If you are driven by numbers and want to save the most money, the Debt Avalanche is your best bet. If you need early wins to stay motivated, the Debt Snowball might be a better fit. The best plan is the one you will actually stick with.
Smart Strategies for Seniors on a Fixed Income
Beyond the core strategies, there are several other tools and tactics that can be particularly helpful for debt payoff in your 60s.
Consider a Home Equity Loan (With Caution)
If you own your home and have built up significant equity, you might consider a home equity loan or a Home Equity Line of Credit (HELOC). This would allow you to borrow against your home’s value, often at a much lower interest rate than credit cards, and use the funds to pay off that high-interest debt.
Why it’s a consideration: It can consolidate multiple high-interest debts into a single, lower-interest monthly payment, potentially freeing up cash flow.
A strong word of caution: This strategy is not without significant risk. Your home is the collateral for the loan. If you are unable to make the payments for any reason, the lender could foreclose and you could lose your home. Never take this step without first consulting with a trusted, independent financial advisor to weigh the pros and cons for your specific situation.
Boost Your Income
While cutting expenses is effective, boosting your income—even slightly—can supercharge your debt payoff plan. You don’t necessarily need to return to a full-time job.
Why it’s effective: Every extra dollar earned can go directly toward your debt principal, as your regular living expenses are already covered by your existing income.
Ideas for seniors: Consider part-time work in a low-stress environment, consulting in your former field, turning a lifelong hobby (like woodworking, crafting, or tutoring) into a small source of income, or renting out a spare room. Downsizing your home is another major move that can free up significant capital to eliminate debt entirely.
Negotiate With Your Creditors
Many people don’t realize this is an option, but you can often negotiate with your credit card companies. They would rather receive a consistent payment than have you default.
How to do it: Call the customer service number on your statement. Be polite and explain that you are a senior on a fixed income and are having difficulty with the payments due to the high interest rate. Ask if they have any hardship programs or if they would be willing to lower your APR to help you pay off the balance. The worst they can say is no, and a successful call could save you thousands.
When to Seek Professional Help
If your debt feels completely overwhelming, or if you are facing calls from collection agencies, please know that you do not have to handle it alone. Seeking guidance is a sign of strength.
A reputable, non-profit credit counseling agency can be an invaluable resource. Counselors from organizations affiliated with the National Foundation for Credit Counseling (NFCC) can help you create a budget, review your options, and may be able to set you up on a Debt Management Plan (DMP). In a DMP, they negotiate with your creditors on your behalf to lower interest rates and consolidate your payments into one manageable monthly sum.
Conclusion: Your Path to Financial Peace
Carrying debt in your 60s can be a heavy burden, but it is one you have the power to lift. By taking an honest look at your finances, creating a realistic budget, choosing a smart strategy, and being persistent, you can systematically work your way toward financial freedom. Remember the steps: assess, budget, strategize, and act.
Imagine a retirement free from the stress of monthly debt payments—a future where your money is truly your own. That future is within your reach. Take the first step today with confidence, knowing you have a clear path to follow.
For expert guidance on senior health and finance, visit Centers for Medicare & Medicaid Services (CMS), Social Security Administration (SSA), Consumer Financial Protection Bureau (CFPB) and Administration for Community Living (ACL).
|
Fact-Checked Content
Our editorial team reviews all content for accuracy and updates it regularly. Learn about our editorial process →
|
Leave a Reply