Practical Steps to Take with Your Refund
Receiving an unexpected $500 payment offers an excellent opportunity to bolster your personal finances. Planning how to deploy these funds helps you maximize their long-term value.
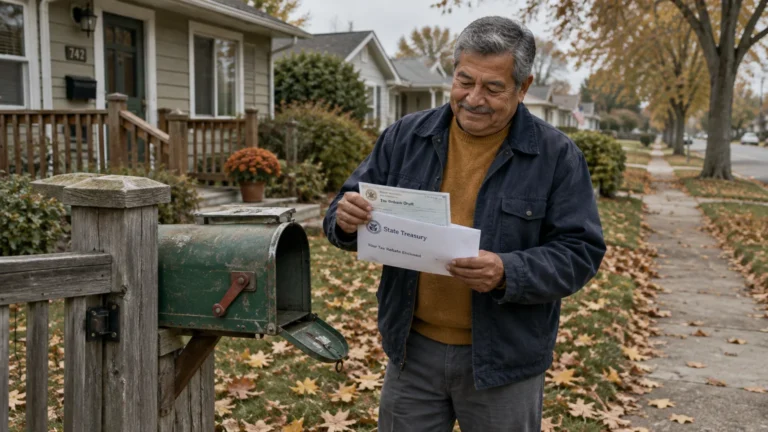
First, verify your recent bank records to see if your funds arrived via direct deposit. Review bank transactions from late September and October 2026 for Treasury notations.
If you receive a paper check, deposit it promptly into an insured bank account. Avoid using expensive check-cashing storefronts that deduct steep fees from your balance.
According to the Social Security Administration (SSA), maintaining accurate banking details safeguards your regular monthly income. Using direct deposit ensures your government funds clear securely without delivery delays.
Consider dedicating your $500 payment toward essential healthcare and retirement priorities:
- Fund your dedicated emergency savings account to manage unpredictable home or auto repairs.
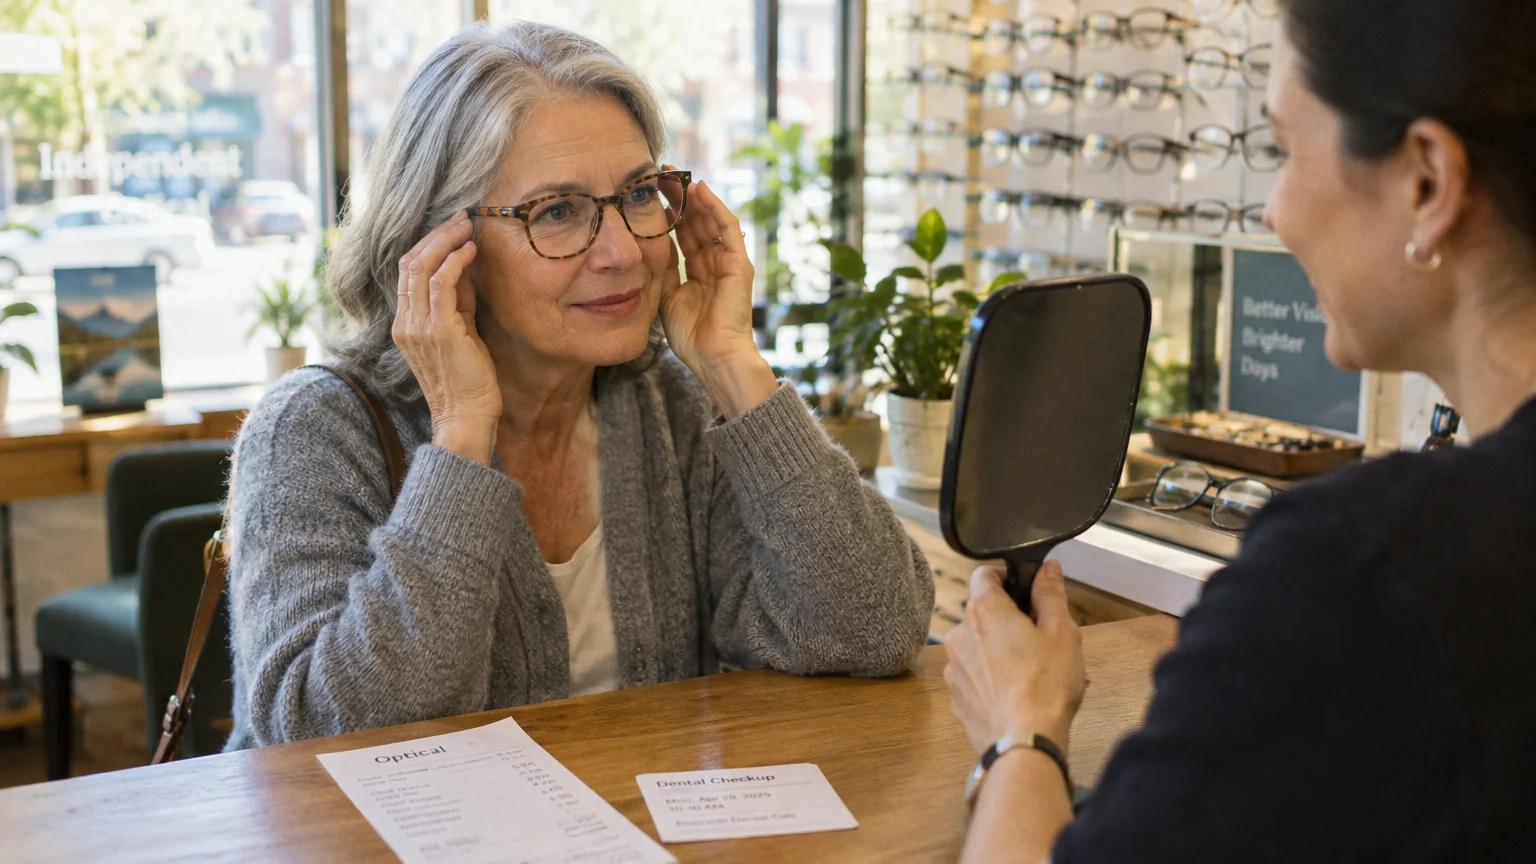
- Prepay upcoming dental, hearing, or vision expenses that standard health insurance rarely covers.
- Establish a cash cushion to help cover prescription drug copayments during the winter months.
- Pay down high-interest credit card debt accumulated from purchasing expensive medical necessities.
If you are an early retiree, set these dollars aside for upcoming health insurance premiums. Even modest savings help cushion your fixed budget while you await Medicare eligibility.
Thoughtful financial planning transforms a modest one-time payment into lasting peace of mind. Every dollar saved reduces financial stress during your retirement years.
Frequently Asked Questions
Do I need to file an application to receive the $500 refund?
No, you do not need to fill out any forms or submit an application. The federal government identifies eligible policyholders automatically using existing marketplace records.
Is the $500 refund considered taxable income on my federal tax return?
Because the payment represents a refund of excess administrative fees you already paid, it is generally non-taxable. Consult your personal tax professional to verify how state and federal rules apply to your return.
Can I get this refund if I receive premium tax credits?
No, policyholders who received federal premium tax credits or other subsidy assistance do not qualify. The program exclusively benefits individuals who paid the entire cost of their monthly premiums out of pocket.
What should I do if I believe I qualify but have not received a payment?
Review your past insurance statements to verify that you held unsubsidized HealthCare.gov coverage in a qualifying state. You can contact HealthCare.gov customer support directly to confirm your historical enrollment status.
Can both my spouse and I receive $500 checks?
Yes, eligibility applies on an individual basis rather than per household. If both spouses held qualifying unsubsidized marketplace plans, your household will receive two separate $500 distributions.
For additional senior resources, visit
American Heart Association, Benefits.gov, National Institute on Aging (NIA), Centers for Disease Control and Prevention (CDC) and Medicare.gov.
Disclaimer: The information in this article is for educational purposes only and is not intended to be a substitute for professional financial, legal, or medical advice. Always consult with a qualified expert for advice tailored to your personal situation.