Moving to a tax-friendly state can save you thousands of dollars each year on pensions, 401(k) withdrawals, and Social Security. Choosing the right location keeps more money in your pocket throughout retirement.
While thirteen states levy zero state income tax on qualified retirement distributions, total living expenses depend on more than just income tax rates. Property taxes, sales taxes, and healthcare costs shape your true annual budget.
This guide covers every state offering tax-free retirement income, key tax rules, and critical hidden costs to evaluate before you pack your bags.
The 13 States With Zero State Tax on Retirement Income
State taxes can take a substantial bite out of your hard-earned nest egg. When you transition from earning a paycheck to drawing down retirement accounts, tax rates directly determine how long your savings will last. Fortunately, thirteen states allow you to draw qualified retirement income without paying a single dime in state income taxes.
These thirteen states fall into two primary categories: nine states that levy no personal state income tax whatsoever, and four states that collect income tax on wages but completely exempt qualified pensions, retirement accounts, and Social Security benefits. Understanding this distinction helps you plan your retirement strategy, especially if you plan to work part-time or generate non-retirement investment income.
| State | Income Tax Type | Social Security Taxed? | Pensions & 401(k)s/IRAs Taxed? | Key Notes for Retirees |
|---|---|---|---|---|
| Alaska | No Income Tax | No | No | Offers annual Permanent Fund Dividend; high overall cost of living. |
| Florida | No Income Tax | No | No | Warm climate, no inheritance tax; higher home insurance and property taxes. |
| Illinois | Flat Income Tax (4.95%) | No | No | Exempts almost all qualified retirement income; high property and sales taxes. |
| Iowa | Graduated Income Tax | No | No | Full exemption on retirement income for residents aged 55 and older. |
| Mississippi | Graduated Income Tax | No | No | Exempts qualified retirement plans and Social Security; lower cost of living. |
| Nevada | No Income Tax | No | No | No tax on income or inheritances; funded heavily by gaming and sales taxes. |
| New Hampshire | No Income Tax | No | No | Fully phased out its interest and dividends tax; high property taxes. |
| Pennsylvania | Flat Income Tax (3.07%) | No | No | Exempts retirement income for adults 59½+; levies state inheritance tax. |
| South Dakota | No Income Tax | No | No | No state income tax; low overall tax burden; colder winter climate. |
| Tennessee | No Income Tax | No | No | No state income tax; higher combined state and local sales taxes. |
| Texas | No Income Tax | No | No | No state income tax; above-average property tax rates. |
| Washington | No Income Tax | No | No | No personal income tax; levies tax on high-value capital gains. |
| Wyoming | No Income Tax | No | No | Low property taxes and no income tax; resource-rich economy. |
States With No Personal Income Tax at All
The simplest way to avoid state taxes on retirement distributions is to live in a state that collects no personal income tax from any source. In these states, your Social Security checks, pension payments, traditional IRA withdrawals, 401(k) distributions, and part-time wages remain 100% free from state-level income taxation.
Nine states operate without a broad-based personal income tax:
- Alaska: Alaska levies no state income tax and no state sales tax. The state also distributes an annual payment to permanent residents through the Alaska Permanent Fund Dividend. However, remote logistics and cold winters make living costs higher than average.
- Florida: Long considered America’s favorite retirement destination, Florida provides zero income tax, zero inheritance tax, and warm weather year-round. Retirees must budget for elevated homeowners insurance premiums and rising real estate values.
- Nevada: Nevada funds its state government through tourism, hospitality, and gaming revenue rather than personal income taxes. Retirees enjoy dry, sunny weather and close proximity to outdoor recreation without paying state income taxes on their savings.
- New Hampshire: New Hampshire has historically taxed dividend and interest income rather than earned wages. The state completed the total phase-out of that dividend and interest tax, making it a complete zero-income-tax state. Keep in mind that New Hampshire relies heavily on local property taxes.
- South Dakota: South Dakota maintains a low overall tax burden, no personal income tax, and no inheritance tax. Its healthcare infrastructure in cities like Sioux Falls and Rapid City caters well to retirees seeking a quiet, affordable lifestyle.
- Tennessee: Tennessee completed the repeal of its Hall Income Tax on investments, ensuring that all retirement distributions, investment dividends, and interest remain tax-free. The state offers a mild four-season climate and low property tax rates.
- Texas: Texas protects all personal earnings and retirement assets from state income taxes under its state constitution. The trade-off comes in the form of property taxes, which rank among the highest in the country.
- Washington: Washington does not tax personal income, wages, or retirement plans. While the state enacted a 7% tax on long-term capital gains exceeding $250,000, that tax exempts retirement accounts, real estate, and standard investment assets held within traditional retirement vehicles.
- Wyoming: Wyoming regularly ranks as one of the most tax-friendly states in the nation. It boasts no personal income tax, low sales taxes, and modest property taxes, making it an exceptional haven for retirees who appreciate mountain living.
States That Tax Regular Income but Fully Exempt Retirement Income
You do not have to relocate to a state without an income tax to enjoy tax-free retirement distributions. Four states levy a standard state income tax on ordinary working wages, yet they completely exempt qualified retirement income for eligible seniors.
If your post-retirement budget relies primarily on distributions from pensions, 401(k)s, 403(b)s, traditional IRAs, and Social Security, these four states treat your funds the same as a zero-income-tax state:
- Illinois: Despite having a flat 4.95% individual income tax rate on standard earned income, Illinois provides one of the most generous retirement exemptions in the country. The state completely exempts Social Security benefits, public and private pensions, government retirement plans, and distributions from qualified traditional IRAs and 401(k) accounts. Non-retirement earnings, such as wages from a post-retirement job, are taxed at the standard flat rate.
- Iowa: Iowa enacted sweeping tax reform that fully exempts retirement income from state personal income taxes for residents aged 55 and older. This exemption covers pensions, annuities, traditional IRAs, and 401(k) distributions. Iowa also exempts all Social Security benefits from state taxation.
- Mississippi: Mississippi exempts all qualified retirement distributions from its state income tax, provided you have reached retirement age under your plan’s rules. This policy covers private pensions, civil service pensions, 401(k) accounts, and traditional IRAs. Mississippi also leaves Social Security benefits untouched.
- Pennsylvania: Pennsylvania levies a flat 3.07% personal income tax on standard wages, but it is exceptionally friendly to retirees. Once you reach age 59½ and retire from employment, distributions from pensions, 401(k)s, and traditional IRAs are completely exempt from state income tax. Pennsylvania does not tax Social Security benefits either.
These four states present an attractive alternative if you want to remain close to family in the Midwest or Mid-Atlantic while shielding your retirement distributions from state taxation.
Where Does Social Security Remain Tax-Free?
Social Security serves as the financial foundation for millions of older Americans. According to the Social Security Administration (SSA), Social Security benefits represent about 30% of the income of older Americans, making tax treatment a vital consideration for your monthly cash flow.
Nationwide, the trend toward eliminating state-level taxes on Social Security benefits continues to accelerate. Today, 41 states and the District of Columbia do not tax Social Security benefits under any circumstances. Missouri, Kansas, and Nebraska completely repealed their state income taxes on Social Security benefits in 2024, and West Virginia completed the final phase-out of its Social Security tax.
Only eight states still levy a state tax on Social Security benefits under certain income thresholds:
- Colorado
- Connecticut
- Minnesota
- Montana
- New Mexico
- Rhode Island
- Utah
- Vermont
Even among these eight states, broad exemptions protect lower- and middle-income seniors from paying the full tax. For example, several of these states use adjusted gross income thresholds; if your total income falls below their target ceiling, your Social Security checks remain entirely untaxed at the state level.
States With Generous Partial Retirement Exclusions
Several states that do not offer complete exemptions still provide substantial exclusions that eliminate or sharply reduce state income taxes for typical retirees. Depending on your total annual withdrawals, moving to one of these states can yield virtually identical tax savings:
- Georgia: Georgia allows an exclusion of up to $65,000 per person aged 65 and older on most types of retirement income, including pensions, interest, dividends, and retirement plan withdrawals. For a married couple where both spouses qualify, that translates to a combined exclusion of $130,000 per year. Georgia also exempts Social Security benefits completely.
- Delaware: Delaware allows individuals aged 60 and older to exclude up to $12,500 of pension and eligible retirement income from state taxation. The state does not tax Social Security and levies no state sales tax.
- Alabama: Alabama offers a unique structure. The state completely exempts defined-benefit pensions (such as state, federal, military, and private corporate pensions) and Social Security benefits. However, Alabama taxes defined-contribution plans, such as traditional 401(k)s and IRAs, offering only a modest $6,000 retirement income exclusion for taxpayers aged 65 and older.
- South Carolina: South Carolina offers a retirement income deduction of up to $15,000 for seniors aged 65 and older on qualified retirement plans and pensions. The state does not tax Social Security benefits.
Hidden Costs in Tax-Free States: Sales, Property, and Inheritance Taxes
State governments must raise revenue to fund roads, public safety, emergency services, and infrastructure. When a state declines to collect revenue through an income tax, it often makes up the shortfall through higher sales taxes, steeper property assessments, or special excise levies. Focusing solely on income tax rates can lead to expensive surprises.
Before packing your moving boxes, examine the complete tax picture:
- High Property Taxes: States like Texas and New Hampshire do not tax your retirement income, but their property tax rates rank among the highest in the country. If you own a high-value home, your annual property tax bill could easily eclipse the income tax savings you gained by moving.
- Escalating Property Insurance: In states like Florida, property insurance premiums have climbed dramatically due to storm and flood risks. An annual home insurance bill of $5,000 to $8,000 can quickly wipe out the benefit of zero state income taxes.
- Elevated Sales Taxes: Tennessee boasts zero income tax, but its combined state and local sales tax average exceeds 9.5%. You pay that tax on nearly everything you buy, including groceries and household necessities. Washington state also pairs its zero-income-tax status with a high state sales tax.
- Inheritance and Estate Taxes: Pennsylvania exempts all retirement income for seniors, but it levies a mandatory state inheritance tax on your estate. Pennsylvania charges between 4.5% and 15% on inherited assets passed to children, siblings, or non-lineal heirs.
- Healthcare Network Changes: Moving to a new state often requires changing your doctors, specialists, and health plans. As you evaluate locations, check plan availability on Medicare.gov to ensure local physicians accept your supplemental coverage or Medicare Advantage network.
Research published by AARP emphasizes that holistic retirement planning requires balancing tax savings against overall cost of living, community amenities, and nearby healthcare facilities.
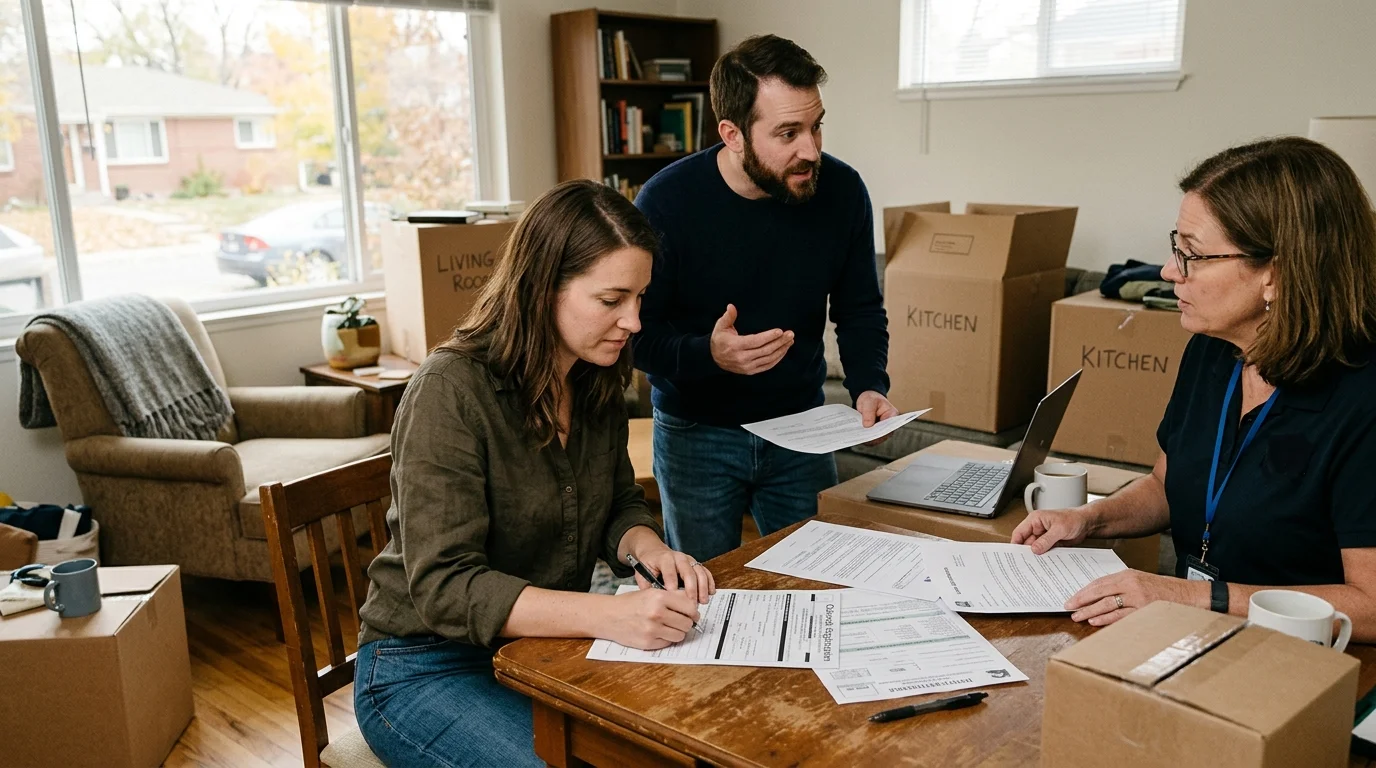
How to Establish Legal Domicile in Your New State
If you relocate from a high-tax state to a tax-free state, your former home state may scrutinize your move. High-tax states like New York, California, and New Jersey frequently conduct residency audits on high-earning retirees who claim to have relocated. To protect yourself from dual taxation, you must clearly establish legal domicile in your new state.
According to consumer guidance from the Consumer Financial Protection Bureau (CFPB), managing legal and financial records carefully protects your assets during major life transitions. Follow these five practical steps to establish your new domicile cleanly:
- Meet the 183-Day Rule: Spend at least 183 days per calendar year in your new state. Keep a detailed log, flight receipts, credit card statements, and utility bills to prove your physical location if audited.
- Update Government Identification: Surrender your old driver’s license and obtain a new one in your destination state within 30 to 60 days of moving. Register to vote in your new municipality and register your vehicles there.
- Establish a Permanent Primary Residence: Purchase or lease a home in your new state and apply for local homestead exemptions if available. Put your utility accounts, internet, and home insurance under your new address.
- Move Financial and Legal Records: Update your address with the IRS, the Social Security Administration, your pension administrators, banks, and investment brokerages. Work with an estate planning attorney to update your will, power of attorney, and healthcare directives under the laws of your new home state.
- Transfer Daily Life Activities: Establish relationships with primary care doctors, dentists, and local places of worship. Relocating your everyday life provides the strongest legal defense against a residency challenge from your former state.
Frequently Asked Questions
Do I still have to pay federal taxes if I move to a state with no income tax?
Yes. State tax laws have no bearing on your federal tax obligations. Regardless of where you live in the United States, you must still pay federal income taxes on traditional IRA distributions, 401(k) withdrawals, taxable pensions, and up to 85% of your Social Security benefits depending on your combined provisional income.
Can my former state tax my pension after I move away?
No. Under the federal Source Tax Act of 1996 (Public Law 104-95), states are strictly prohibited from taxing retirement income and pensions earned within their borders if the recipient is now a legal resident of another state. Once you properly establish domicile in a tax-free state, your former state cannot claim taxes on your qualified retirement distributions.
What happens if I work a part-time job in a state that exempts retirement income?
Your tax treatment depends on the specific state. In the nine states with no personal income tax (such as Florida, Texas, or Tennessee), all wages from your part-time job remain state-income-tax-free. In the four states that exempt retirement distributions but maintain an income tax (Illinois, Iowa, Mississippi, and Pennsylvania), your part-time earned wages will be subject to state income tax, even though your pension and 401(k) withdrawals remain untaxed.
Why does Pennsylvania exempt retirement distributions but tax inheritance?
Pennsylvania structures its tax policy to support resident retirees during their lifetime by exempting Social Security, qualified pensions, and IRA distributions for individuals age 59½ and older. To generate state revenue, Pennsylvania collects a state inheritance tax when assets transfer to heirs after death, with rates ranging from 0% for surviving spouses up to 15% for non-family beneficiaries.
How do I know if my pension is considered “qualified” for state tax exemptions?
Most standard private employer pensions, federal civil service annuities, military pensions, and state or municipal retirement plans meet the definition of qualified plans under state tax codes. However, non-qualified deferred compensation plans (such as Section 457(f) plans for executives) may not receive the same tax exemptions. Review your plan documents or consult a certified financial planner to verify your plan’s tax status.
For additional senior resources, visit
Centers for Medicare & Medicaid Services (CMS),
Social Security Administration (SSA),
Consumer Financial Protection Bureau (CFPB),
Administration for Community Living (ACL) and
Eldercare Locator.
Disclaimer: The information in this article is for educational purposes only and is not intended to be a substitute for professional financial, legal, or medical advice. Always consult with a qualified expert for advice tailored to your personal situation.

Leave a Reply