Managing your retirement budget requires a sharp eye, especially when inflation stretches fixed incomes thinner than expected. Lowering your monthly household expenses provides immediate financial relief and long-term peace of mind. By taking a closer look at everyday recurring charges, you can find hidden savings without sacrificing the services you rely on. From evaluating your healthcare premiums to adjusting your utility usage and trimming unnecessary subscriptions, practical adjustments make a significant impact. You have the power to renegotiate rates, switch providers, and eliminate wasteful spending with just a few phone calls. Uncovering these savings allows you to redirect funds toward travel, family, or building an emergency cushion, ultimately securing a more comfortable and stress-free retirement.
Evaluating Your Cable and Internet Services
Cable and internet bills are notorious for creeping up over time. Providers frequently offer attractive introductory rates that double or even triple once the promotional period expires. If you have been with the same provider for several years, you are likely paying a “loyalty penalty.” Service providers rely on customer complacency, assuming you will simply pay the higher rate rather than go through the hassle of switching or negotiating.
You can push back against these regular rate hikes. The first step involves reviewing your current statement to understand exactly what you are paying for. Look for obscure fees, equipment rental charges, and premium channels you rarely watch. Many older adults discover they are paying monthly rental fees for a modem or router that would cost less than $100 to purchase outright. Buying your own equipment pays for itself in less than a year and eliminates that recurring monthly charge.
Once you understand your bill, pick up the phone. Call your provider’s customer service line and ask to speak with the cancellation or retention department. These representatives possess the authority to offer discounts and promotions that frontline agents cannot access. Use the following steps to navigate the conversation:
- Do your homework: Look up promotional offers from competing providers in your area before you call.
- State your intention clearly: Politely explain that your current bill is too high for your retirement budget and you are considering switching to a competitor.
- Ask for a better deal: Request that they match the competitor’s pricing or apply a new promotional discount to your account.
- Review your tier: If they cannot lower the price of your current package, ask if you can downgrade your internet speed or channel lineup to a more affordable tier without losing the channels you watch most.
If you mainly watch local news and network television, consider dropping cable entirely. An inexpensive digital antenna provides high-definition local channels for free. Paired with a basic internet connection, you can dramatically reduce your entertainment expenses.
Reassessing Your Cell Phone and Data Plans
Much like internet services, mobile phone plans constantly evolve. If you are holding onto a legacy plan from five or ten years ago, you are likely overpaying for data limits or features you do not need. Major carriers aggressively market unlimited data plans, but the reality is that most seniors spend the majority of their time connected to home Wi-Fi. If you only use cellular data for occasional GPS navigation or checking email on the go, an unlimited plan wastes your money.
The telecommunications industry now features numerous Mobile Virtual Network Operators (MVNOs). These smaller companies rent tower space from the major carriers, meaning you get the exact same network coverage at a fraction of the cost. Brands specifically catering to older adults offer straightforward, no-contract plans that cost significantly less than mainstream unlimited packages.
Take time to monitor your actual data usage. Most smartphones feature a setting that tracks exactly how many gigabytes of data you consume each month. If your usage falls below three or four gigabytes, a customized, low-data plan will serve you perfectly while keeping your bill under $30 a month.
Additionally, always ask about age-based discounts. According to resources provided by AARP, maintaining an active membership can unlock significant monthly discounts on select cellular plans, accessories, and activation fees. Even a seemingly small discount of 10% can add up to substantial savings over the course of a year. Do not hesitate to call your current provider to ask if they offer a specific senior plan—many major carriers have unadvertised 55+ plans available only to customers who explicitly request them.
Reviewing Medicare Supplements and Health Insurance
Healthcare often ranks as the most significant expense in retirement, making it a critical area to review annually. Many seniors adopt a “set it and forget it” mentality regarding their Medicare coverage. Unfortunately, this approach can lead to hundreds of dollars in wasted premiums or excessive out-of-pocket costs at the pharmacy.
Insurance companies adjust their premiums, deductibles, and drug formularies every single year. A Medicare Part D prescription drug plan that offered the lowest prices for your medications last year might have dropped your specific drugs from their preferred list this year. During the Medicare Annual Enrollment Period (AEP)—which runs from October 15 through December 7—you have the opportunity to switch plans.
To ensure you secure the most cost-effective coverage, compile a list of your current prescriptions, including dosages and frequency. Utilize the official plan finder tool available through Medicare.gov. By entering your zip code and medications, the system will display exactly which Part D or Medicare Advantage plan offers the lowest total estimated cost for your specific health needs.
Beyond traditional premiums, investigate Medicare Savings Programs (MSPs) if your income is limited. These state-administered programs help pay for Medicare Part A and Part B premiums, and in some cases, deductibles and copayments. Even if you think you might not qualify, the income thresholds adjust annually, making it worth a quick phone call to your State Health Insurance Assistance Program (SHIP) to verify your eligibility.
Bundling and Updating Home and Auto Insurance
Insurance premiums for your home and vehicle slowly climb over time due to inflation, rising repair costs, and regional risks. If you simply pay your renewal notice each year without questioning the amount, you are missing an opportunity to save. Financial experts generally recommend shopping your property and casualty insurance rates every two to three years.
Start by evaluating your auto insurance. Retirees typically drive far fewer miles than working professionals. If you no longer commute daily, you may qualify for a low-mileage discount. Call your agent and update your estimated annual mileage. Furthermore, many insurance companies offer substantial discounts for seniors who complete an approved defensive driving course. These courses are frequently available online and can reduce your premium by 5% to 10% for up to three years.
Next, look at your homeowners insurance. Ensure your coverage limits reflect the actual cost to rebuild your home, not the current real estate market value, which fluctuates wildly. You can also save money by increasing your deductibles. Raising your auto or home deductible from $500 to $1,000 significantly lowers your monthly or annual premium. Just ensure you keep that $1,000 set aside in an emergency savings account should you ever need to file a claim.
Finally, consolidate your policies. “Bundling” your home and auto insurance with the same carrier remains one of the easiest ways to secure a quick discount. If your policies are currently with two different companies, ask both providers to quote a bundled package and go with the more competitive offer.
Shrinking Your Monthly Energy and Utility Costs
Utility bills fluctuate wildly with the seasons, making budgeting on a fixed income highly stressful. A brutally cold winter or a sweltering summer can easily result in an electric or gas bill that breaks your monthly budget. Fortunately, you can take control of these essential expenses through usage adjustments and billing programs.
First, contact your utility providers and ask to be placed on a “budget billing” or “levelized billing” plan. These programs calculate your average annual energy usage and divide it into twelve equal monthly payments. While this does not reduce the total amount you pay over the year, it eliminates unpredictable spikes, allowing you to budget with precision.
Next, conduct a basic home energy audit. Small behavioral changes yield noticeable savings over time. Lower your water heater temperature to 120 degrees Fahrenheit. Swap out old incandescent light bulbs for energy-efficient LEDs. During extreme weather, utilize fans to circulate air, allowing you to adjust your thermostat by a few degrees without sacrificing physical comfort.
If you face difficulty managing energy costs, help is available. The Low Income Home Energy Assistance Program (LIHEAP) provides federally funded assistance to help seniors cover heating and cooling costs. To locate community-based organizations that administer these funds locally, you can explore resources provided by the Administration for Community Living (ACL), which connects older adults with vital community support services.
Trimming Unused Subscription and Membership Fees
In today’s digital economy, businesses love the subscription model. For consumers, however, these recurring charges easily blend into the background of a credit card statement. A $10 streaming service here and a $15 delivery fee there quickly snowball into hundreds of dollars a year in automated expenses.
Set aside an hour this week to review your last three months of bank and credit card statements. Highlight any recurring charge you do not immediately recognize or no longer actively use. You might be surprised to find you are still paying for a magazine you never read, a premium channel you watched for one specific show, or a fitness app you abandoned months ago.
Use the following table to help you identify common subscription traps and evaluate whether they deserve a place in your budget:
| Expense Category | Common Examples | Action Required to Save |
|---|---|---|
| Streaming Video | Netflix, Hulu, Prime Video | Rotate active services. Keep one or two per month, pause the rest. |
| Health & Fitness | Gyms, Diet apps, Yoga platforms | Cancel paid gyms; check if your Medicare plan includes SilverSneakers. |
| Retail & Delivery | Instacart, Amazon Prime, Walmart+ | Assess if the delivery savings outweigh the annual membership fee. |
| Digital Media | Newspapers, Audiobooks, Music | Switch to free library apps like Libby or Hoopla for reading and listening. |
When you decide to cancel a service, do it immediately. Do not tell yourself you will do it next month. Companies make subscribing incredibly easy but often build friction into the cancellation process. Push through the inconvenience; removing these financial leaks creates instant breathing room in your monthly budget.
Uncovering Property Tax Exemptions for Seniors
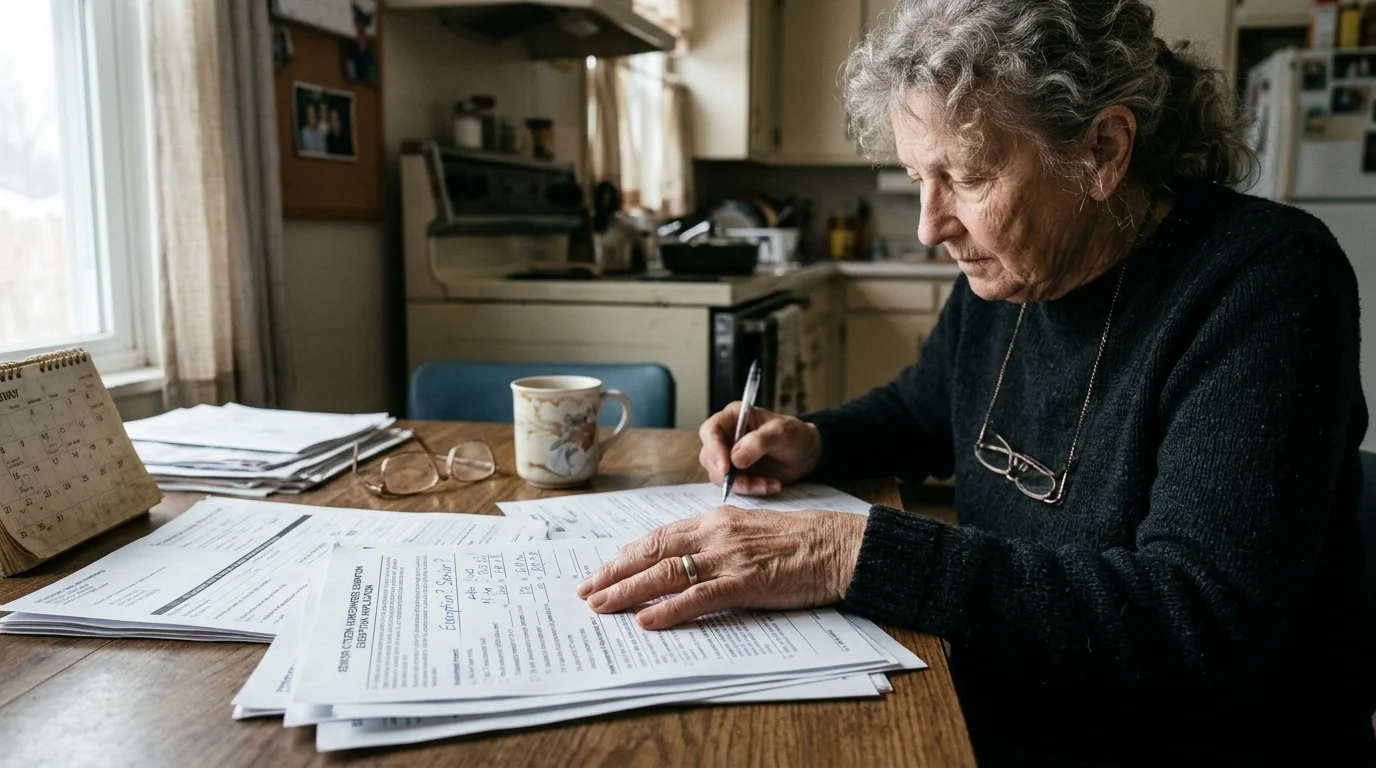
For homeowners who have paid off their mortgages, property taxes often represent the largest housing expense. As local property values rise, so do the tax assessments, placing a heavy burden on retirees trying to age in place. Thankfully, almost every state offers some form of property tax relief specifically designed for older adults.
The most common forms of relief include senior property tax exemptions and property tax freezes. An exemption reduces the taxable value of your home. For example, if your home is assessed at $250,000 and you receive a $50,000 senior exemption, you only pay taxes on $200,000. A property tax freeze, on the other hand, locks in the assessed value of your home at a certain age, protecting you from future tax hikes even if the housing market surges.
These programs are rarely automatic. You must proactively apply for them through your county assessor’s office or local tax authority. Requirements vary wildly by municipality; some are based strictly on age (usually kicking in at 65), while others have strict income limits. Gather your recent tax returns, proof of age, and proof of residency, and contact your local assessor’s office to find out exactly what relief programs are available in your jurisdiction.
Common Billing Scams to Avoid
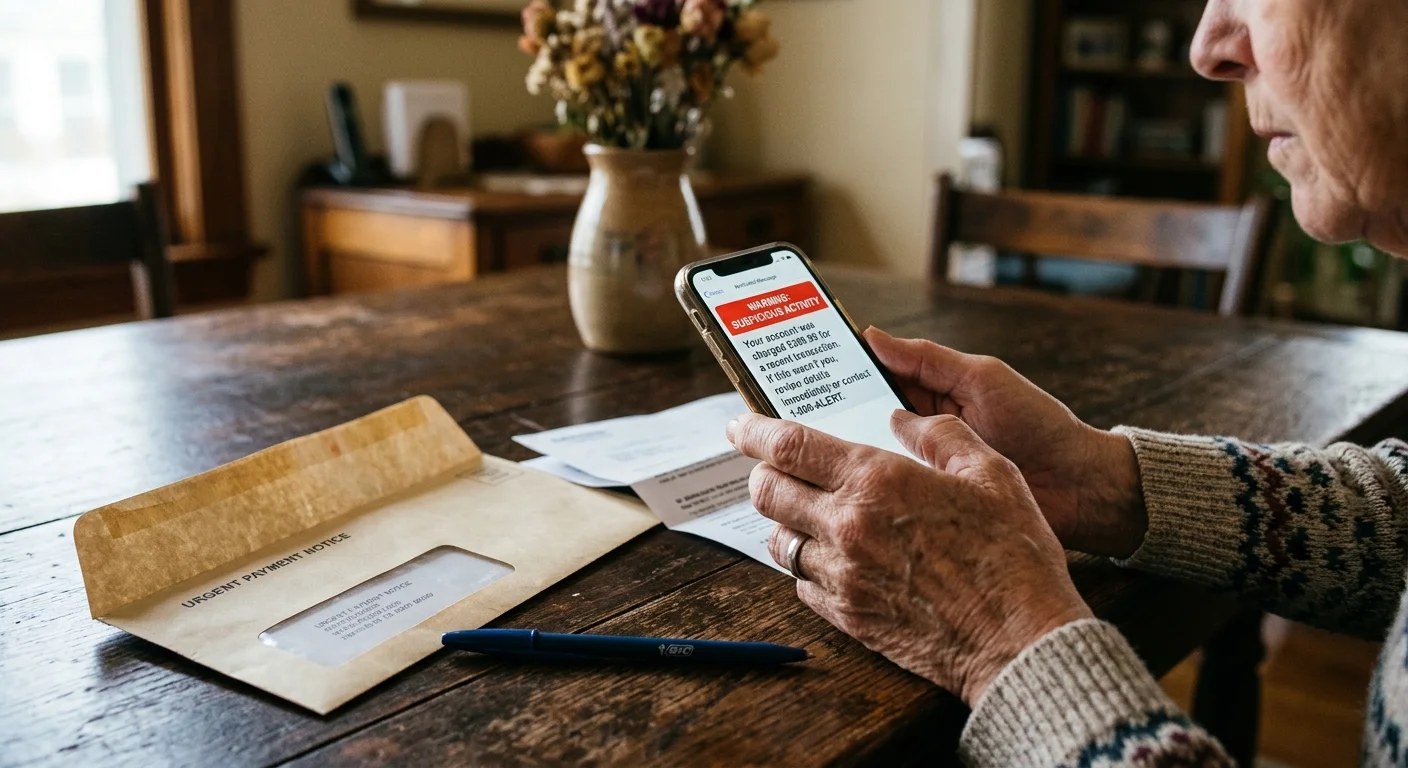
While looking for ways to lower your monthly expenses, you must also protect the money you already have. Seniors are frequent targets for billing scams, where fraudsters impersonate trusted service providers to steal money or sensitive personal information.
A prevalent scheme involves the “utility shut-off” scam. A caller pretending to be from your local electric or water company claims your payment is past due and threatens to disconnect your service immediately unless you pay over the phone. Real utility companies will never demand immediate payment via wire transfer, prepaid debit card, or gift card. If you receive a call like this, hang up immediately. Find your most recent utility bill and dial the official customer service number printed on the paper to verify your account status.
Similarly, be wary of third-party companies offering to lower your credit card interest rates or negotiate your bills for an upfront fee. These “debt settlement” scams often leave you worse off. According to guidelines from the Consumer Financial Protection Bureau (CFPB), you should never pay an upfront fee for debt relief services. You have the ability to call your creditors and negotiate payment plans or interest rate reductions yourself, entirely for free.
Always protect your Medicare number just as fiercely as your Social Security number. Scammers often call offering “free” medical supplies or genetic testing, asking for your Medicare details to bill the government fraudulently. This can exhaust your medical benefits and leave you liable for unexpected costs.
Frequently Asked Questions
How often should I review my monthly bills?
You should conduct a thorough review of your recurring expenses at least once a year. A good practice is to schedule this audit around a major event, such as tax season or the Medicare Annual Enrollment Period. However, you should review your cell phone and internet statements every few months just to ensure no sudden rate hikes or hidden fees have been applied to your account.
Will calling my service provider actually lower my bill?
Yes, in many cases, making a phone call yields positive results. Customer retention is highly valuable to service providers. They would rather offer you a $20 monthly discount than lose you to a competitor entirely. The key is to be polite, firm, and prepared with knowledge of what competing companies are charging for similar services in your area.
Can I change my Medicare plan at any time to save money?
Generally, no. You can only switch your Medicare Advantage or Medicare Part D prescription drug plan during the Annual Enrollment Period (AEP), which runs from October 15 through December 7 each year. However, certain life events—such as moving to a new state or losing other health coverage—may qualify you for a Special Enrollment Period (SEP), allowing you to make changes outside the standard window.
What is a senior property tax freeze?
A senior property tax freeze is a program offered by some local governments that prevents your property taxes from increasing once you reach a certain age, typically 65. It locks in the assessed value of your home, so even if neighborhood home values skyrocket, your tax bill remains stable. You must usually apply for this program through your county tax assessor, and it often involves income restrictions.
How can I keep track of all my automatic subscriptions?
The easiest method is to route all your recurring subscriptions through a single credit card. This isolates your automatic charges, making them much easier to review each month. Alternatively, you can use your smartphone’s application store settings (like the Apple App Store or Google Play) to view and manage any subscriptions you initiated on your mobile device. Regularly reviewing your monthly credit card statement remains the best defense against forgotten charges.
For additional senior resources, visit
Consumer Financial Protection Bureau (CFPB), Administration for Community Living (ACL), Eldercare Locator, AARP and Alzheimer’s Association.
Disclaimer: The information in this article is for educational purposes only and is not intended to be a substitute for professional financial, legal, or medical advice. Always consult with a qualified expert for advice tailored to your personal situation.
Leave a Reply