Helpful Resources for Seniors
Helpful Resources for Seniors Navigate life's next chapter with confidence
  • Home
  • Lifestyle
  • Well-Being
  • Finance

Passive Income Streams Every Retiree Should Know

September 8, 2025 · Finance

A senior's face in profile, smiling gently under warm lamplight while looking at a blooming orchid plant in the evening.

Actionable Strategies and Money-Saving Tips

Now, let’s move from theory to practice. Here are some of the most effective and accessible passive income streams for retirees, along with practical steps you can take to implement them.
An older woman in her early 70s sits on a sunlit porch, gently smiling as she sips tea. A tablet displays a financial graph beside her.
Enjoying the peace of mind that comes with smart investments.

1. Create an Income Stream with Dividend-Paying Stocks

Investing in solid, dividend-paying companies can be an excellent way to generate a rising stream of income. Focus on established businesses with a long track record of profitability and dividend payments, often called “blue-chip” stocks. Companies known as “Dividend Aristocrats” are those in the S&P 500 index that have increased their dividend for at least 25 consecutive years.

How it works: You buy shares of a company, and in return, they pay you a regular dividend, typically every quarter.

Example: Imagine you invest $20,000 in a stock that has a dividend yield of 3%. This would generate $600 per year ($20,000 x 0.03) in passive income, or $150 per quarter, without you ever having to sell the stock itself. If the company increases its dividend, your income grows.

Action Step: Consider a Dividend ETF (Exchange-Traded Fund). Instead of picking individual stocks, an ETF allows you to buy a basket of dozens or hundreds of dividend-paying stocks in a single transaction. This provides instant diversification, which significantly reduces your risk.
An older couple in their late 60s at a kitchen table, planning a trip using a large map. Financial documents are discreetly visible.
Dreaming up new adventures, supported by a strong financial plan.

2. Secure Your Principal with Bonds and Fixed-Income

Bonds are essentially loans you make to a government or a corporation. In exchange for your loan, the issuer promises to pay you regular interest payments (called “coupons”) over a set term and then return your original investment (the “principal”) when the bond “matures.” For retirees focused on safety, U.S. Treasury securities (T-bills, T-notes, and T-bonds) are considered one of the safest investments in the world.

How it works: You purchase a bond, collect interest payments twice a year, and get your principal back at the end of the term.

Example: You buy a 10-year U.S. Treasury note for $10,000 with a 4% coupon rate. You will receive $400 in interest payments each year ($10,000 x 0.04), paid in $200 increments every six months. After 10 years, the government returns your original $10,000.

Action Step: Explore building a “bond ladder.” This involves buying several bonds with different maturity dates (e.g., 2-year, 4-year, 6-year). As each shorter-term bond matures, you can reinvest the principal into a new, longer-term bond. This strategy helps you adapt to changing interest rates and ensures you have access to a portion of your money every couple of years.
An older woman with gray hair sits at a bright kitchen island, sipping tea and looking at a tablet displaying charts.
Finding peace of mind with careful financial planning at home.

3. Use High-Yield Savings Accounts and CDs for Safety

For money that you need to keep completely safe and accessible, high-yield savings accounts (HYSAs) and Certificates of Deposit (CDs) are your best friends. They are FDIC-insured up to $250,000 per depositor, per bank, which means your principal is protected. While they offer lower returns than stocks or bonds, they provide unmatched peace of mind.

How it works: An HYSA offers a variable interest rate that is typically much higher than a traditional savings account. A CD offers a fixed interest rate for a specific term (e.g., 1 year, 5 years), but you will pay a penalty if you withdraw the money early.

Example: If you deposit $25,000 into an HYSA with a 4.5% annual percentage yield (APY), you would earn approximately $1,125 in interest over one year.

Action Step: Shop around online for the best rates. Online banks often offer significantly higher rates on HYSAs and CDs than traditional brick-and-mortar banks because they have lower overhead costs.
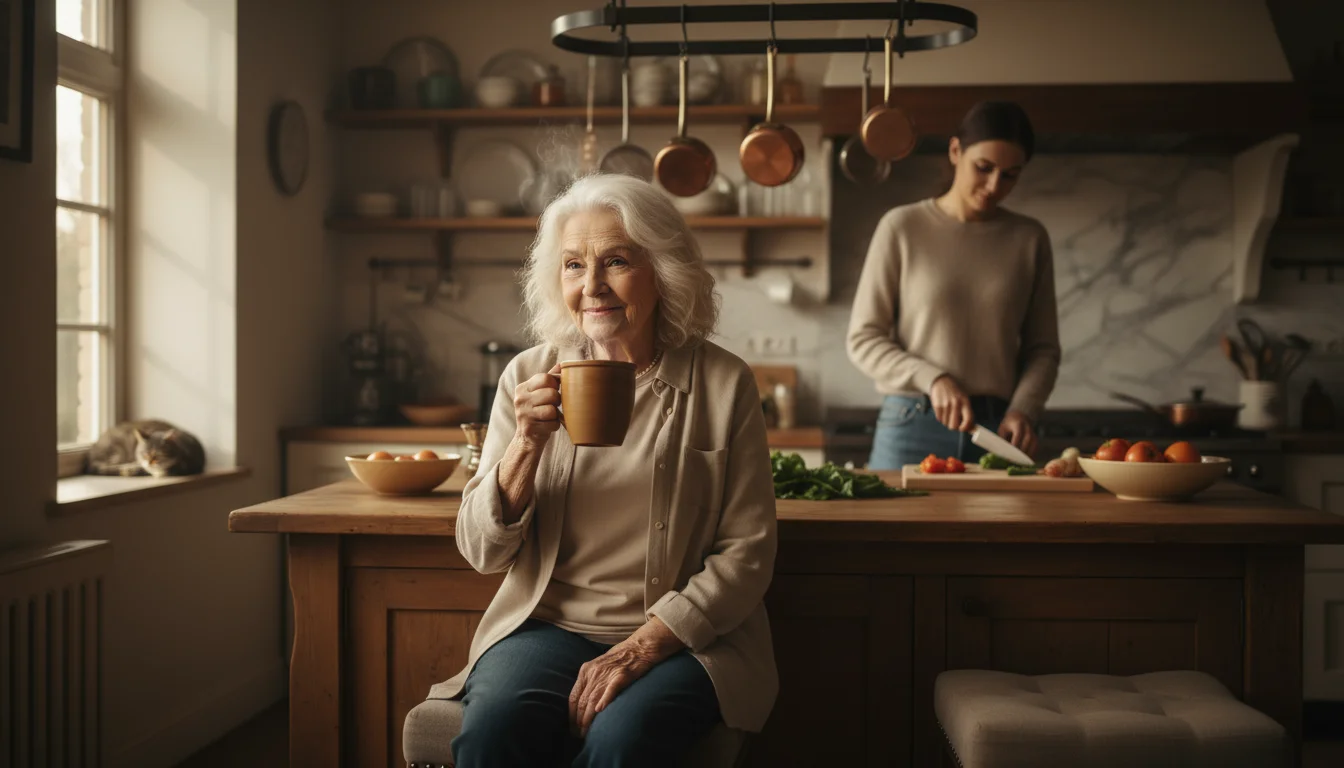
An older woman sips tea at her kitchen island, watching a younger adult prepare food in the background of their shared, sunlit kitchen.
Sharing a comfortable home and a warm moment in the kitchen.

4. Generate Cash Flow from Real Estate

For those comfortable with property ownership, real estate can be a powerful income generator. This doesn’t necessarily mean buying a new property.

  • Rent a Room in Your Home: If you have a spare bedroom, renting it out can generate hundreds of dollars each month. It’s a great way to leverage an asset you already own and can also provide companionship.
  • Consider a Duplex or Accessory Dwelling Unit (ADU): Living in one unit and renting out the other can cover a significant portion of your mortgage and property taxes.
  • Invest in REITs: If you don’t want the hassle of being a landlord, a Real Estate Investment Trust (REIT) is an excellent alternative. REITs are companies that own and operate income-producing real estate. You can buy shares of a REIT on the stock exchange, just like a stock, and you receive a portion of the rental income as a dividend.

Example: If you invest $15,000 in a REIT with a 5% dividend yield, you would receive $750 in annual passive income, without ever having to deal with a tenant.
An older man stands at his mailbox, gently opening a white envelope with a look of quiet contentment on his face.
Opening mail that brings peace of mind every month.

5. Explore the Guarantees of an Annuity

Annuities can play a role in a retirement plan by providing a guaranteed income stream you cannot outlive. A simple, immediate fixed annuity is the most straightforward: you give an insurance company a lump sum of money, and they start sending you a check every month for the rest of your life.

How it works: The size of your payment depends on your age, gender, the amount you invest, and current interest rates. The trade-off for this guarantee is that you typically lose access to your principal.

Example: A 65-year-old man might invest $100,000 in an immediate annuity and receive a guaranteed payment of around $550 every month for life.

Action Step: Stick to simple, low-cost annuity products. Be very wary of complex variable or indexed annuities with high fees and long surrender periods. Always have a trusted financial advisor review any annuity contract before you sign.

For official information on Social Security and Medicare, visit SSA.gov and Medicare.gov. Federal tax information is at the IRS.

To protect yourself from scams and for consumer information, consult the Consumer Financial Protection Bureau (CFPB) and the FTC.
Pages: 1 2 3 4 5 6

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • A red backpack stands open on a wooden table beside a clear pouch organizing identity, insurance, and banking papers. 9 Financial Documents to Keep in an Emergency Go-Bag
  • A woman sits at a wooden dining table reviewing a printed Social Security earnings record with a pencil in hand. 9 Signs Your Social Security Statement Has an Error
  • An older man with a satchel and scarf walks along a brick university campus path beneath autumn trees. 10 College Towns With Tuition Perks for Seniors
  • Senior couple sitting at a wooden dining table reviewing tax documents, a 1040 form, and using a calculator. 8 Things Retirees Can Deduct That Younger Filers Can't
  • An older couple sits at a sunlit wooden dining table reviewing paperwork and writing in a notebook together. 11 Small Financial Moves That Quietly Doubled a Nest Egg
  • Older couple holding mugs on a stone balcony overlooking a Mediterranean coastal town and harbor at sunrise. 12 Small Countries Where Retirees Are Quietly Buying Property
  • An older couple sits at a sunlit wooden table reviewing paperwork and financial documents together. 10 Things That Change About Social Security After a Spouse Remarries
  • A senior man reviews tax forms at a wooden table beside a calculator, coffee mug, and Form 1040 documents. 11 Things That Trigger an IRS Audit for Retirees Specifically
  • A senior woman sits at a wooden kitchen table holding eyeglasses, looking over papers beside a calendar and mug. 8 Things That Happen to Benefits During a Government Shutdown
  • A mature couple sitting at a wooden kitchen table reviewing retirement pension paperwork beside a steaming mug of coffee. 10 Pension Plan Terms Every Retiree Should Actually Understand

Newsletter

Get the latest posts delivered to your inbox.

Related Articles

A senior using a tablet to manage their retirement finances, with organized paperwork and a calculator visible nearby.

Financial Tools and Trackers Designed for Seniors

Welcome. Navigating your financial life during retirement presents a unique set of opportunities and challenges.…

Read More →
A sunlit home office desk with a financial planner, reading glasses, and a digital frame showing a photo of a smiling elderly man.

The Ultimate Guide to Maximizing Social Security Benefits

Table of Contents Introduction: Taking Control of Your Finances in Retirement Understanding the Financial Basics…

Read More →
A senior couple looking at a tablet in a bright kitchen, appearing happy and relieved.

5 Prescription Drug Discounts Seniors Are Missing

Discover five proven prescription drug discounts seniors are missing, including Extra Help guidelines, cash-pay savings,…

Read More →
A senior couple smiles while unpacking fresh groceries from canvas bags onto a wooden kitchen island in a warm, sunlit kitchen.

10 Grocery Chains Offering the Best Loyalty Perks in 2026

Discover the 10 best grocery loyalty programs in 2026 offering senior discounts, low-cost delivery, and…

Read More →
A senior citizen examines financial documents, such as a budget and investment statements, while sitting at a desk with a computer.

Understanding Inflation and What It Means for Your Nest Egg

You worked hard for decades, carefully saving and planning for a comfortable retirement. You built…

Read More →
An older couple in their living room, calmly looking at a pension statement together, conveying peace of mind.

Understanding Your Pension Options: Lump Sum vs. Annuity

Understanding Your Pension Options: Lump Sum vs. Annuity As you approach retirement, or if you…

Read More →
A happy senior couple looking at a tablet in a bright, modern kitchen.

10 Things You Should Never Pay Full Price for After 60

Discover 10 things seniors should never pay full price for, including property taxes and cell…

Read More →
FBI’s World Cup Ticket Scam Warning

FBI’s World Cup Ticket Scam Warning

Protect your savings from the FBI's World Cup ticket scam warning with our practical guide…

Read More →
Senior man sitting at a wooden desk reviewing paperwork near open books, eyeglasses, and a steaming mug.

5 Financial Perks Reserved Just for Veterans in Retirement

Discover five valuable financial perks reserved for senior veterans in retirement, including healthcare savings, long-term…

Read More →
Helpful Resources for Seniors Helpful Resources for Seniors

Navigate life's next chapter with confidence

Inedit Agency S.R.L.
Bucharest, Romania

contact@helpfulresourcesforseniors.com

Explore

  • Home
  • About Us
  • Editorial Policy
  • Privacy Policy
  • Terms and Conditions
  • Subscribe
  • Unsubscribe
  • Contact
  • Request to Know
  • Request to Delete
  • CA Private Policy

Categories

  • Finance
  • Lifestyle
  • Well-Being

© 2026 Helpful Resources for Seniors. All rights reserved.