Planning for the future is one of the most profound acts of care you can undertake for your loved ones. It’s about more than just numbers and legal documents; it’s about creating a legacy of security, clarity, and peace of mind. As a financial professional dedicated to helping seniors navigate their retirement years, I know that the world of estate planning can sometimes feel complex and even a little intimidating. My goal here is to demystify the process and provide you with clear, actionable guidance.
As we navigate 2025, there are several crucial updates and timeless strategies that every senior should be aware of. These changes can directly impact how you protect your assets and provide for your family. This guide is designed to empower you with the knowledge you need to make informed decisions for your unique situation.
This article is for informational purposes only and is not intended to be financial or legal advice. Please consult with a qualified estate planning attorney or financial professional for advice tailored to your individual situation.
Understand the Imminent “Sunset” of the Current Estate Tax Exemption
The ‘Why’: This is arguably the most critical and time-sensitive estate planning topic of 2025. The Tax Cuts and Jobs Act of 2017 nearly doubled the federal estate tax exemption. For 2025, this exemption stands at a historic high of $13.61 million per individual. However, this provision is set to “sunset” or expire on December 31, 2025. On January 1, 2026, the exemption is scheduled to revert to its pre-2018 level, which is estimated to be around $7 million per person after adjusting for inflation. This means that many more families could find their estates subject to a federal tax of up to 40% on assets above that lower threshold. Acting now, while the exemption is high, is a key strategy for preserving your wealth for your heirs.
The ‘How’:
- Assess Your Net Worth: Start by getting a clear picture of your total estate value. This includes your home, investments, retirement accounts, business interests, and valuable personal property.
- Consult a Professional: This is not a DIY situation. Schedule a meeting with an estate planning attorney and a financial advisor. They can run projections to see if your estate might be affected by the 2026 changes.
- Consider Strategic Gifting: You can use the current high exemption to make significant gifts to family members now without incurring gift tax. This “locks in” the use of the higher exemption amount. This is a powerful legacy planning tool that can remove assets from your taxable estate permanently.
- Explore Advanced Trusts: For those with larger estates, now is the time to discuss strategies like a Spousal Lifetime Access Trust (SLAT) or an Irrevocable Life Insurance Trust (ILIT) with your attorney.
Review and Update ALL Your Beneficiary Designations
The ‘Why’: Many people assume their will controls where all their assets go. This is a common and costly mistake. Assets with beneficiary designations—such as life insurance policies, 401(k)s, IRAs, and annuities—pass directly to the person named on the form, regardless of what your will states. These designations are a direct contract with the financial institution that supersedes your will. An outdated beneficiary (like an ex-spouse or a deceased relative) can lead to your hard-earned assets going to the wrong person, sparking family disputes and legal battles. Regular reviews are a cornerstone of effective senior estate planning.
The ‘How’:
- Create a Master List: Compile a list of every account you own that has a beneficiary. This includes retirement accounts, life insurance policies, annuities, and any “Payable on Death” (POD) or “Transfer on Death” (TOD) bank or brokerage accounts.
- Request and Verify: Contact each financial institution to request a copy of your current beneficiary designation form. Don’t rely on memory. Verify the primary and contingent (secondary) beneficiaries listed.
- Update After Life Events: Make it a habit to review these forms after any major life event: a marriage, divorce, the birth of a child or grandchild, or the death of a beneficiary.
- Coordinate with Your Will: Ensure your beneficiary choices align with the overall goals of your estate plan. If there’s a discrepancy, discuss it with your financial advisor or attorney to ensure your intentions will be met.
Factor the SECURE 2.0 Act into Your Retirement Account Legacy
The ‘Why’: The original SECURE Act and its successor, SECURE 2.0, have significantly changed the rules for those who inherit retirement accounts. For most non-spouse beneficiaries (like your children or grandchildren), the “stretch IRA” is gone. They are now generally required to withdraw the entire balance of an inherited IRA or 401(k) within 10 years of your passing. This can push them into a higher tax bracket and accelerate the tax bill on these funds. This is one of the most important wills and trusts updates to consider, as it may change how you structure the inheritance of your tax-deferred accounts.
The ‘How’:
- Educate Your Heirs: Have a transparent conversation with your beneficiaries. Make sure they understand the 10-year withdrawal rule and the potential tax consequences so they can plan accordingly.
- Consider Roth Conversions: You might consider converting some of your traditional IRA funds to a Roth IRA during your lifetime. While you’ll pay the income tax now, the withdrawals your heirs make from the inherited Roth IRA will be completely tax-free, eliminating the 10-year tax bomb.
- Explore Trust Strategies: Naming a specially designed trust as the beneficiary of your IRA can provide more control. An “accumulation trust” can receive the funds and manage the distributions over time, protecting the assets and preventing a beneficiary from spending it all at once. This requires careful drafting by a qualified attorney.
Evaluate if a Revocable Living Trust Is Right for You
The ‘Why’: While a will is an essential document, it has one major drawback: it must go through probate. Probate is the court-supervised process of validating a will and distributing assets. It can be time-consuming (often taking months or even years), expensive (with court fees and attorney costs), and is a public process, meaning your family’s finances become a public record. A Revocable Living Trust is a powerful alternative that allows your assets to be transferred to your heirs privately and efficiently, completely avoiding probate for the assets held within the trust.
The ‘How’:
- Consult an Estate Attorney: Setting up a trust is more complex than writing a will. Work with a qualified attorney to draft a trust document that reflects your exact wishes for how your assets should be managed and distributed.
- Choose Your Trustee: You will be the trustee during your lifetime, maintaining full control. You must also name a “successor trustee” who will step in to manage the trust’s assets upon your incapacitation or death.
- Fund the Trust: This is the most crucial step. A trust only controls the assets it owns. You must retitle your major assets (like your home’s deed, non-retirement investment accounts, and bank accounts) into the name of the trust. Your attorney will guide you through this process.
Solidify Your Healthcare Directives and Powers of Attorney
The ‘Why’: Comprehensive estate planning is about planning for your life, not just for after you’re gone. What if you become ill or injured and are unable to make your own medical or financial decisions? Without legal documents in place, your family may have to go to court to get the authority to act on your behalf, a stressful and costly process known as guardianship or conservatorship. Having these documents in place ensures your wishes are respected and empowers the person you trust to manage your affairs, providing immense relief to your loved ones during a difficult time.
The ‘How’:
- Create a Durable Power of Attorney for Finances: This legal document names an “agent” to manage your financial affairs if you become incapacitated. They can pay bills, manage investments, and file taxes on your behalf.
- Establish a Healthcare Proxy (or Medical Power of Attorney): This document names a healthcare agent to make medical decisions for you if you cannot. Choose someone you trust implicitly to understand and honor your values.
- Draft a Living Will: This document, also known as an advance directive, states your wishes regarding end-of-life medical care, such as the use of life support. It guides both your family and your doctors.
- Share and Store Securely: Give copies of these documents to your agents and your doctor. Keep the originals in a safe, accessible place and let your family know where to find them.
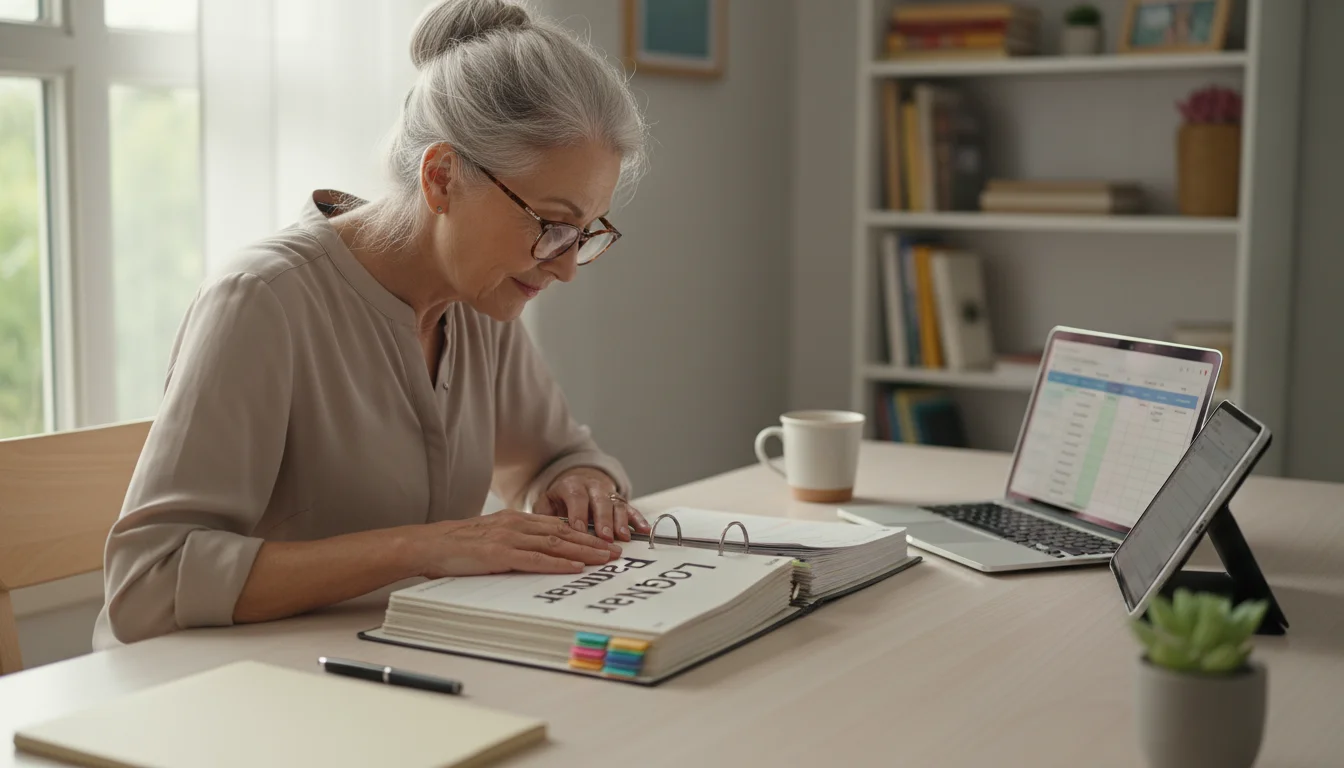
Organize Your Digital Assets and Create a “Legacy” Binder
The ‘Why’: Our lives are increasingly online. Your legacy planning must account for this reality. Think about everything from online banking and investment portals to social media accounts, cloud photo storage, and email. If your executor doesn’t have access to this information, critical financial assets could be lost, bills could go unpaid, and precious digital memories could be locked away forever. Organizing this information is a modern necessity for a smooth estate settlement.
The ‘How’:
- Inventory Your Digital Life: Create a list of all your digital accounts. Include usernames, passwords, and security question answers. Don’t forget utilities, streaming services, social media, and shopping sites.
- Choose a Secure Storage Method: You can use a physical notebook or binder stored in a secure location (like a safe). Alternatively, you can use a secure digital password manager and provide instructions to your executor on how to access the master password.
- Provide Instructions: For each account, state your wishes. Should your Facebook account be memorialized or deleted? Should your photo library be downloaded and shared with family? This guidance is invaluable.
- Inform Your Executor: The most important step is to tell your executor or successor trustee that this list exists and where to find it. A secret list is a useless list.
For expert guidance on senior health and finance, visit National Institute of Mental Health (NIMH), National Institutes of Health (NIH), Centers for Medicare & Medicaid Services (CMS), Social Security Administration (SSA) and Consumer Financial Protection Bureau (CFPB).
|
Fact-Checked Content
Our editorial team reviews all content for accuracy and updates it regularly. Learn about our editorial process →
|
Leave a Reply