Choosing when to claim retirement benefits shapes your monthly cash flow for decades. Your claiming age dictates whether you receive a reduced check, your base amount, or a boosted payout.
In 2026, the average Social Security check ranges from $1,424 at age 62 up to $2,275 or more at age 70. Knowing these numbers helps you choose the right filing timeline for your financial security.
We break down payment amounts, early penalties, and delayed credits below. This claiming age benefit comparison gives you clear guidance so you can collect every dollar you have earned.
Understanding Your Full Retirement Age in 2026
Your Full Retirement Age—often abbreviated as FRA—serves as the cornerstone of your retirement calculations. It represents the exact age when you qualify for 100% of your earned benefit.
According to the Social Security Administration (SSA), anyone born in 1960 or later reaches Full Retirement Age at exactly 67. If you were born in 1959, your FRA arrives at 66 years and 10 months.
The government determines your baseline check, called the Primary Insurance Amount (PIA), using your 35 highest-earning working years. Those earnings are indexed for wage growth over your career.
If you worked fewer than 35 years, the agency fills in the missing years with zeros. Those zero-earning years drag down your lifetime monthly average.
In 2026, the maximum taxable wage base rises to $184,500. Earnings up to this threshold face the 6.2% payroll tax and count toward your future benefit.
The Average Social Security Check at Age 62
Age 62 is the earliest point at which you can file for retired worker benefits. Millions of seniors choose this option each year to secure immediate income.
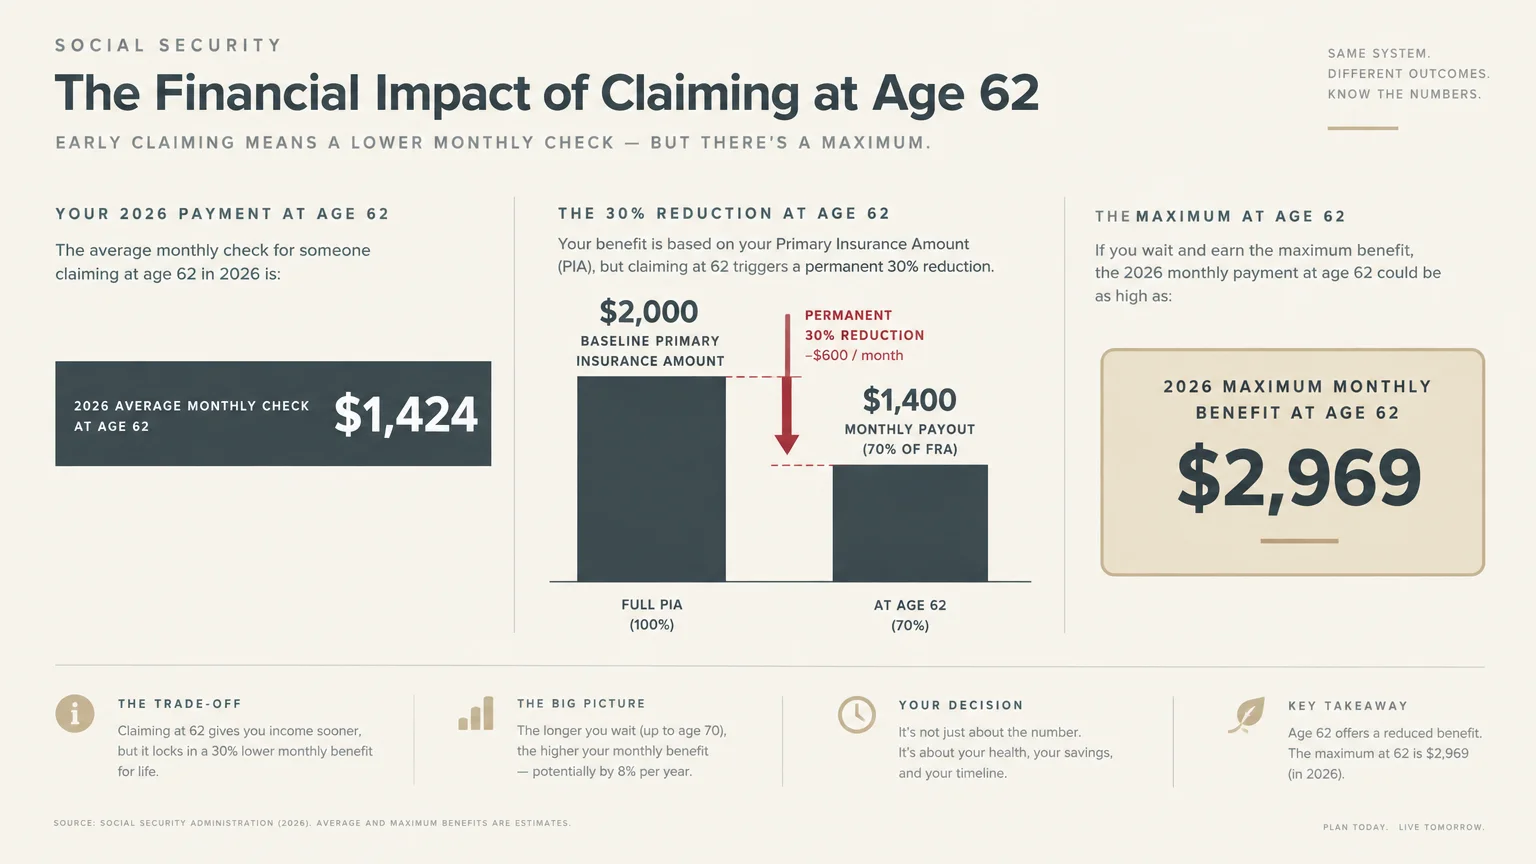
In 2026, the average Social Security check at age 62 is approximately $1,424 per month. This figure represents the lowest average payout among all retired age groups.
Filing at 62 triggers a permanent 30% reduction against your Primary Insurance Amount. You receive only 70% of the monthly payment you would have collected at 67.
For example, a monthly baseline benefit of $2,000 drops down to just $1,400 if you claim early. That reduction remains in effect for the rest of your life.
High earners who paid maximum payroll taxes throughout their careers face a strict cap. In 2026, the maximum possible monthly benefit at age 62 is $2,969.
Many seniors file early due to urgent health problems, unexpected job loss, or caregiving duties. While early money helps in an emergency, the permanent cut requires careful household budgeting.
The Average Social Security Check at Age 67
Reaching age 67 marks a major milestone for workers born in 1960 or later. Claiming at this point grants you 100% of your Primary Insurance Amount without penalties.
In 2026, the average Social Security check at age 67 reaches approximately $2,016 per month. This payment reflects an unreduced, full-rate baseline benefit.
Across all retired workers of every age, the overall average benefit sits between $2,071 and $2,086 per month. Waiting until 67 brings you right alongside this national benchmark.
High earners who reach their FRA in 2026 receive significantly larger payments. The maximum monthly check at age 67 ranges between $4,152 and $4,207.
Filing at 67 provides a stable foundation if you plan to retire fully from the workforce. It protects your cash flow without forcing you to wait into your seventies.
The Average Social Security Check at Age 70
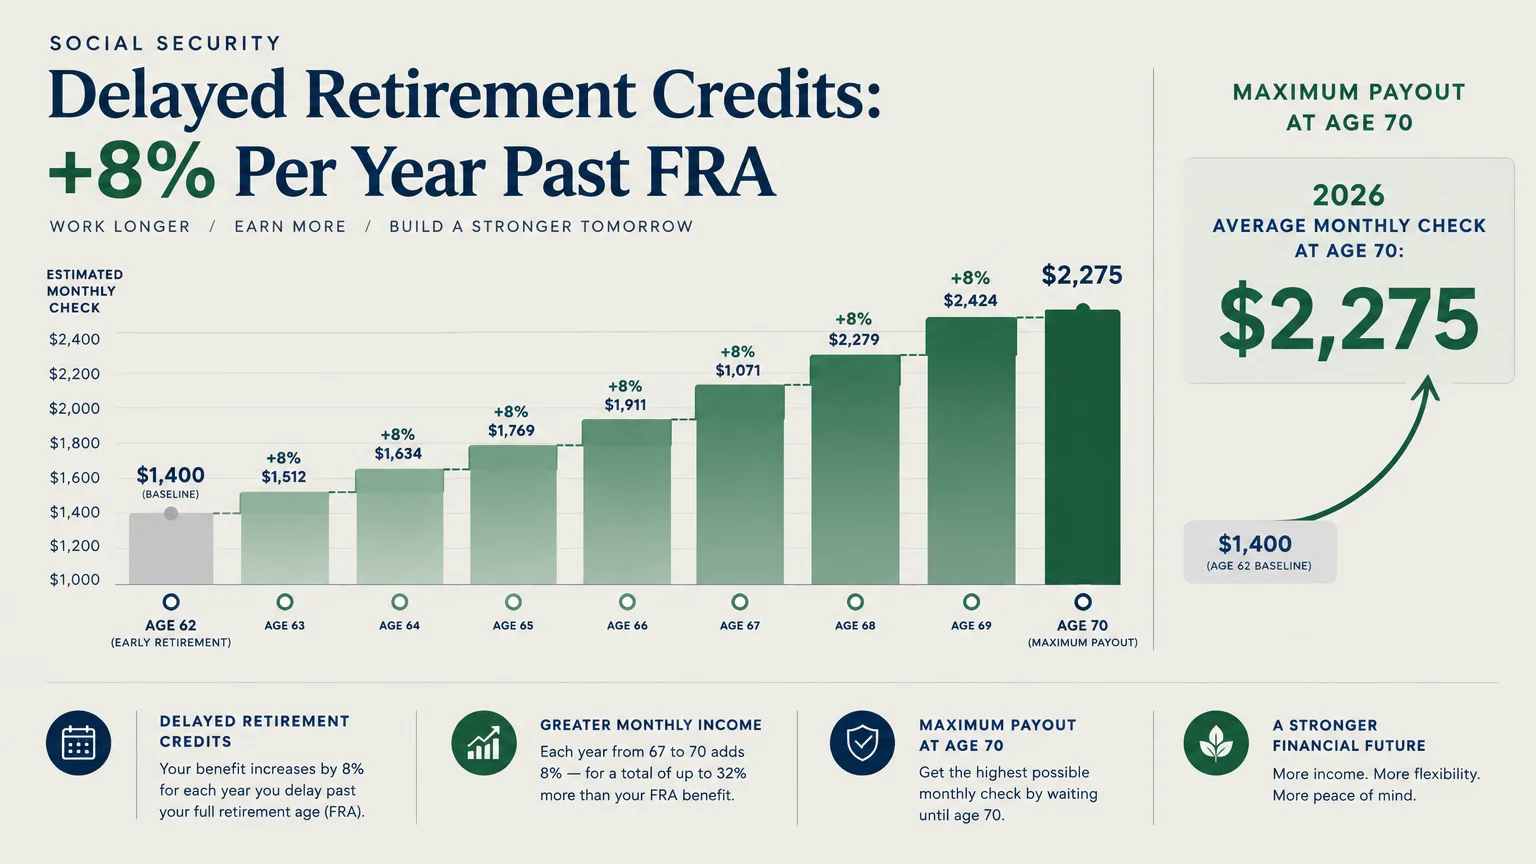
Delaying your claim past your Full Retirement Age yields substantial financial growth. Each month you wait past 67 earns you delayed retirement credits.
These credits accumulate at a rate of 8% per year, or approximately 0.67% each month. Waiting until age 70 produces a permanent 24% increase over your baseline amount.
In 2026, the average benefit across all 70-year-old recipients is roughly $2,275 per month. This broad statistic includes beneficiaries who claimed earlier in life.
For retirees who purposefully delayed claiming until age 70, the financial payoff is much higher. Their average monthly payment exceeds $3,030.
The maximum monthly check at age 70 climbs to between $5,181 and $5,251 in 2026. This tier represents the highest standard retirement payout available under federal law.
Delayed retirement credits stop accumulating the month you turn 70. Delaying your claim past your 70th birthday provides zero additional benefit and leaves money on the table.
Comparing Benefits Across Claiming Ages
Evaluating how much Social Security pays requires comparing both monthly checks and lifetime payouts. The gap between age 62 and age 70 is substantial.
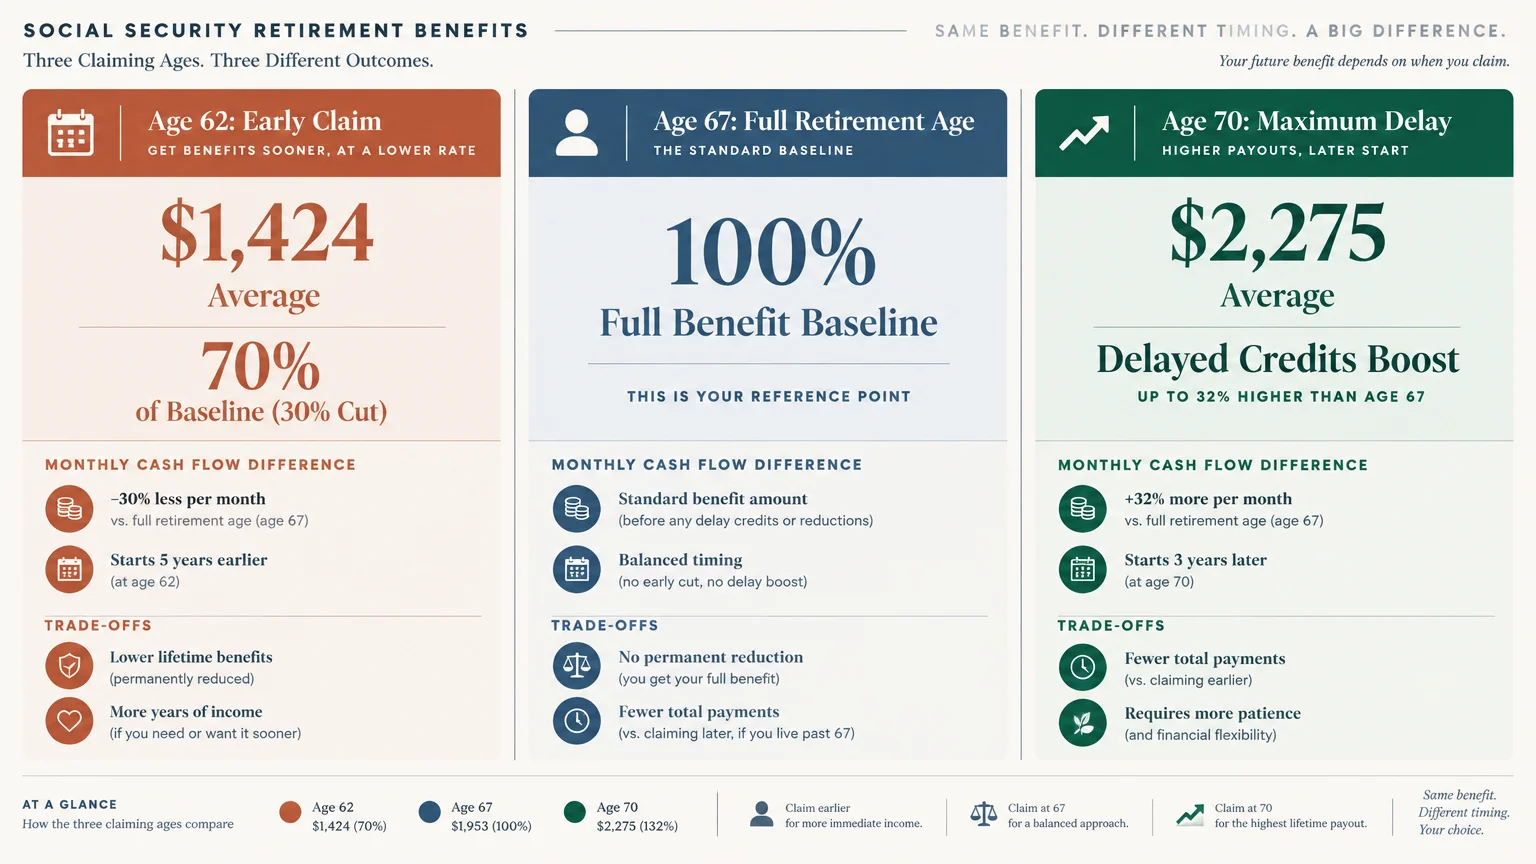
A retiree collecting $1,424 at 62 receives $851 less each month than someone collecting $2,275 at 70. Over a full calendar year, that difference equals more than $10,200.
| Claiming Age | Benefit Status | Average Monthly Check (2026) | Maximum Monthly Check (2026) | Percent of Full Benefit |
|---|---|---|---|---|
| Age 62 | Earliest Eligibility | $1,424 | $2,969 | 70% |
| Age 67 | Full Retirement Age | $2,016 | $4,152 – $4,207 | 100% |
| Age 70 | Maximum Delayed Credits | $2,275 (Overall) / $3,030+ (Delayed) | $5,181 – $5,251 | 124% |
The break-even age represents the moment where delayed filing produces more cumulative lifetime cash than claiming early. For most retirees, this cross-over occurs between ages 78 and 82.
If you live past age 80, waiting until 67 or 70 generates greater total lifetime income. If you face serious health concerns, claiming earlier often delivers greater total cash.
Working While Receiving Benefits: Earnings Test Rules
Many older adults continue working part-time or full-time after filing for retirement benefits. If you claim before Full Retirement Age, the government limits your earned income.
The Retirement Earnings Test applies strict thresholds until you reach age 67. In 2026, the baseline earnings limit sits at $24,480 per year.
If you earn more than $24,480, the agency withholds $1 in benefits for every $2 earned above the cap. These rules apply to wages and net self-employment earnings.
During the calendar year you reach 67, the restriction eases significantly. The agency deducts $1 for every $3 earned above $65,160 before your birthday month.
Once you reach your 67th birthday, the earnings test disappears entirely. You can earn an unlimited income without losing a single dollar of your monthly check.
Withheld money is not permanently forfeited. When you turn 67, the agency recalculates your monthly benefit upward to credit back the withheld amounts over time.
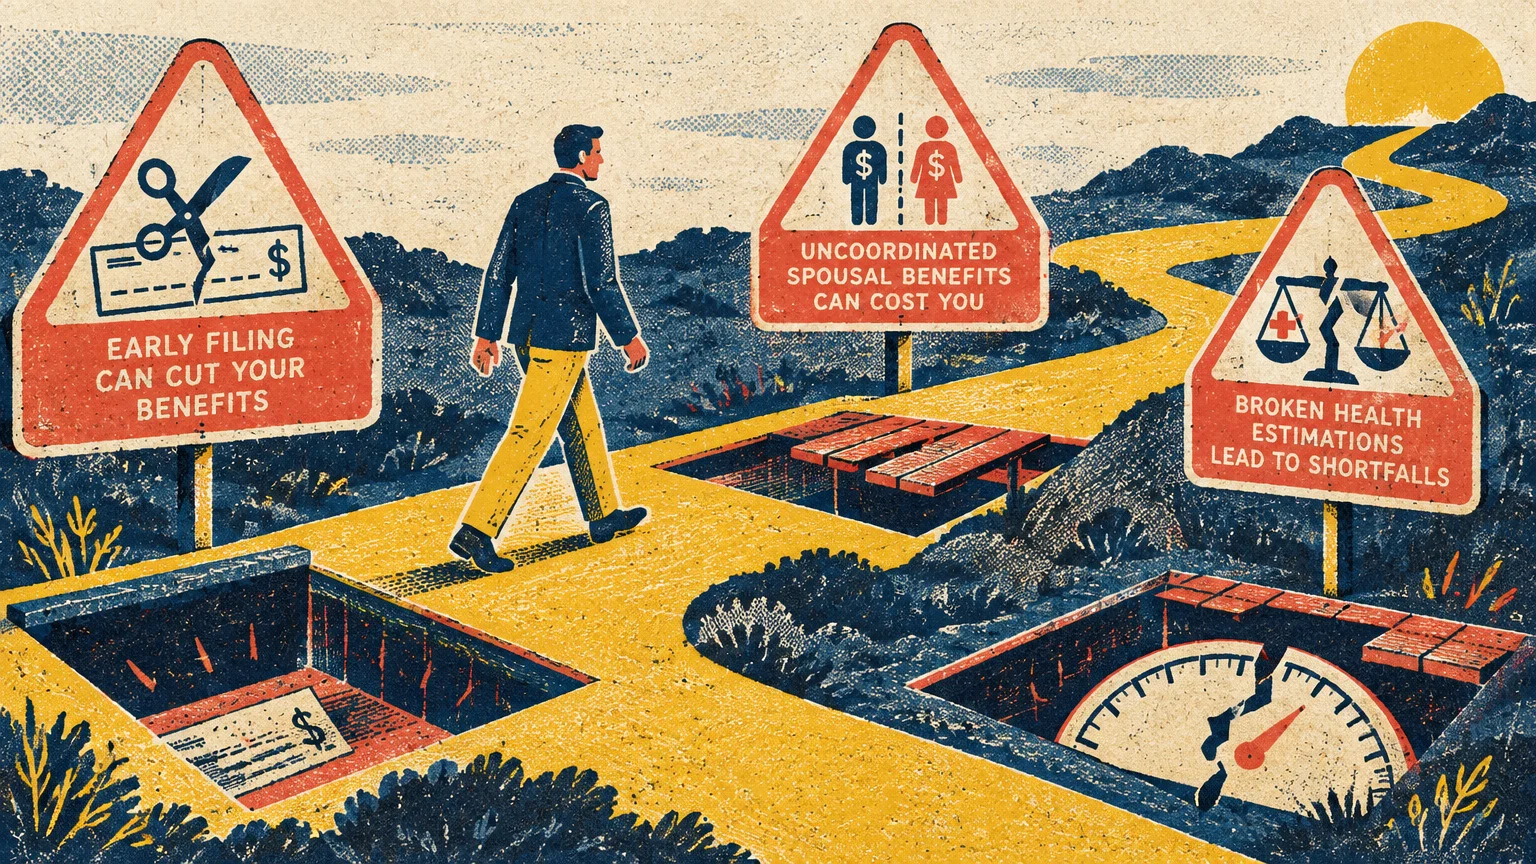
Critical Mistakes to Avoid When Claiming
Rushing into a filing decision without exploring the rules can cost you thousands of dollars. Avoid these common missteps before submitting your application.
One widespread error involves confusing Social Security claiming with Medicare enrollment. Guidance on Medicare.gov emphasizes signing up at age 65, even if you plan to delay Social Security until 70.
Missing your Medicare Initial Enrollment Period can trigger lifelong premium surcharges. Always coordinate your health insurance timeline separately from your pension decisions.
Another major mistake involves overlooking survivor benefits for a spouse. If you are the higher-earning spouse, claiming at 62 permanently caps the survivor check your partner inherits later.
Retirees also frequently forget about federal income taxes on benefits. Up to 85% of your Social Security income becomes taxable if your combined provisional income exceeds statutory thresholds.
Finally, stay alert against phone and email impersonation scams targeting seniors. According to consumer alerts from the Consumer Financial Protection Bureau (CFPB), official agencies never call to demand money or threaten your benefits.
How to Decide Your Best Claiming Age
Finding the right claiming age requires balancing personal health, career plans, and household cash needs. No single claiming age fits every older American.
Consider your family health history and personal longevity projections first. If longevity runs in your family and you enjoy strong health, delaying payments offers powerful longevity insurance.
Evaluate your other financial assets, such as traditional IRAs, 401(k) accounts, and home equity. Drawing down private savings between 62 and 67 allows your guaranteed benefit to grow.
Review your spouse’s earning history and age difference carefully. A coordinated claiming strategy often involves having the lower-earning partner claim early while the primary earner delays until 70.
Follow these practical steps to prepare your filing plan:
- Create a personal account on the official Social Security portal to inspect your recorded earnings history.
- Review your estimated benefits at ages 62, 67, and 70 to identify discrepancies or missing working years.
- Audit your recurring monthly living expenses to calculate your baseline income floor.
- Speak with a fiduciary financial advisor to model federal tax obligations on your future checks.
Taking control of these figures early removes guesswork and secures your standard of living throughout retirement.
Frequently Asked Questions
Can I change my mind after claiming benefits at age 62?
Yes; you have a one-time option to withdraw your application within 12 months of filing. You must repay every dollar received, which resets your earnings record for future increases.
Do annual cost-of-living adjustments apply if I wait until age 70?
Yes; Cost-of-Living Adjustments (COLA) apply to your underlying benefit regardless of whether you claim. All annual inflation increases compound into your eventual check starting at age 62.
How many months before my chosen retirement date should I file?
You should submit your formal application three months before you want your first benefit check to arrive. This lead time gives the agency sufficient window to process paperwork smoothly.
Does claiming early reduce my spouse’s future survivor benefit?
Yes; a surviving spouse inherits the exact monthly payment the deceased worker was receiving. Filing early permanently reduces the financial lifeline your spouse receives if you pass away first.
Will my monthly benefit check increase if I delay past age 70?
No; delayed retirement credits terminate completely upon your 70th birthday. Delaying beyond age 70 provides no benefit increase and results in the permanent loss of monthly checks.
For additional senior resources, visit
AARP, Alzheimer’s Association, American Heart Association and Benefits.gov.
Disclaimer: The information in this article is for educational purposes only and is not intended to be a substitute for professional financial, legal, or medical advice. Always consult with a qualified expert for advice tailored to your personal situation.

Leave a Reply