Helpful Resources for Seniors
Helpful Resources for Seniors Navigate life's next chapter with confidence
  • Home
  • Lifestyle
  • Well-Being
  • Finance

Top 10 Tax Deductions Most Seniors Miss

September 8, 2025 · Finance

A close-up of a senior's hands caring for a houseplant. Their contented face is softly visible in the background under warm lamplight.

The Top 10 Tax Deductions Most Seniors Miss

Now, let’s explore the key deductions and tax benefits that can significantly lower your tax bill. Review this list carefully to see which ones apply to your financial situation.
An older man and his adult daughter sit on a sofa, reviewing a document. The daughter points, and the man smiles with understanding.
Understanding new tax benefits with family support.

1. The Higher Standard Deduction for Seniors

This is the easiest and most common tax benefit for seniors, yet some forget to claim it, especially if filing on their own for the first time. The IRS allows you to increase your standard deduction if you or your spouse are age 65 or older. You get an additional amount if you are legally blind.

How it works: For the 2023 tax year (filed in 2024), a single individual under 65 gets a standard deduction of $13,850. If you are 65 or older, you can add an extra $1,850, bringing your total standard deduction to $15,700. If you are married and filing jointly, and both you and your spouse are 65 or older, you both get the additional amount, increasing your standard deduction by $3,100 total.
An older woman and her adult daughter review health-related documents together at a bright kitchen counter.
Reviewing important medical papers with family.

2. Medical and Dental Expense Deductions

This is perhaps the most significant itemized deduction for retirees. Healthcare costs often rise with age, and the tax code provides some relief. You can deduct the portion of your total medical expenses that exceeds 7.5% of your Adjusted Gross Income (AGI).

How it works: First, calculate 7.5% of your AGI. Let’s say your AGI is $50,000. That threshold would be $3,750 ($50,000 x 0.075). Next, add up all your qualifying medical expenses for the year. If your total was $8,000, you could deduct the amount that is over the threshold: $8,000 – $3,750 = $4,250.

Commonly missed deductible expenses include:

  • Premiums for Medicare Part B and Part D.
  • Premiums for supplemental health insurance (Medigap).
  • Premiums for long-term care insurance (subject to age-based limits).
  • Out-of-pocket costs for prescription drugs, dental care (including dentures), eyeglasses, and hearing aids.
  • Transportation costs to and from medical appointments (you can deduct a standard mileage rate or actual costs like gas and oil).
  • Costs for in-home care if it is primarily for medical purposes.

Keep meticulous records and receipts for all medical-related spending throughout the year. For official federal tax information, you can always visit the IRS.
Older man at a wooden desk, hand on a financial form, next to a charity brochure, looking thoughtful. Tea and glasses on desk.
Thinking about smart ways to give back and save on taxes.

3. Qualified Charitable Contributions (QCDs)

If you are charitably inclined and are over age 70½, a Qualified Charitable Distribution (QCD) is a fantastic tax-saving tool. A QCD allows you to donate up to $100,000 directly from your IRA to a qualified charity. This is more powerful than a standard donation because the money is excluded from your taxable income. It also counts toward your Required Minimum Distribution (RMD), satisfying that obligation without increasing your income.

How it works: Instead of taking your RMD, having it taxed, and then writing a check to charity, you instruct your IRA custodian to send the funds directly. This lowers your AGI, which can help you qualify for other deductions and potentially reduce your Medicare premiums.
An older man in a brightly lit garage sits at a utility table, reviewing a property tax bill and car sales receipt with a calculator.
Carefully considering property and sales taxes for the best deduction.

4. State and Local Taxes (SALT)

If you itemize, you can deduct state and local taxes, but this deduction is capped at $10,000 per household, per year. This includes a combination of property taxes and either state income taxes or state sales taxes. Most people deduct their income tax, but if you live in a state with no income tax or made a very large purchase (like a car), deducting sales tax might be more beneficial.
A contented older couple, mid-70s, stands arm-in-arm on the front walk of their sunlit house, looking back at it. A 'SOLD' sign is clearly visible in
Embracing new beginnings after selling their long-time family home.

5. The Home Sale Exclusion

Many seniors decide to downsize in retirement. If you sell your primary home, you can exclude a significant amount of the profit from capital gains tax. A single filer can exclude up to $250,000 of gain, and a married couple filing jointly can exclude up to $500,000. To qualify, you must have owned and used the home as your main residence for at least two of the five years leading up to the sale.
Older woman in her 70s carefully sorting bills and financial papers on a wooden kitchen table in soft window light.
Carefully reviewing finances in the quiet morning light.

6. Credit for the Elderly or Disabled

This is a tax credit (remember, that’s a dollar-for-dollar reduction of your tax bill) designed for lower-income seniors. The eligibility rules are quite strict, which is why it is often missed. You must be age 65 or older OR retired on permanent and total disability. Your income must fall below certain limits. For example, for a single person, your AGI must be under $17,500, and your non-taxable Social Security benefits must be under $5,000. While the limits are low, it can provide meaningful relief for those who qualify.
An older couple sits at a dining table, looking at a tablet and tax documents. The man gestures towards the screen.
Working together to understand your Social Security benefits.

7. Tax-Free Social Security Benefits

This isn’t a deduction, but it’s a critical rule that helps you keep more of your money. Depending on your “combined income” (your AGI plus non-taxable interest plus one-half of your Social Security benefits), a portion of your Social Security benefits may be tax-free.

  • If your combined income is below $25,000 (for single filers) or $32,000 (for married couples), your benefits are not taxed.
  • If your income is between $25,000 and $34,000 (single) or $32,000 and $44,000 (married), up to 50% of your benefits may be taxable.
  • If your income is above those higher thresholds, up to 85% of your benefits may be taxable.

Understanding these thresholds can help you manage your other retirement withdrawals to minimize the tax on your Social Security income. For the most accurate details on your benefits, visit SSA.gov.
An older man with reading glasses intently reviews financial statements at his home desk, a pen poised over a notepad with calculations.
Thoroughly reviewing investment statements for tax-saving details.

8. Investment or Brokerage Fees

While the 2017 tax law eliminated the deduction for investment advisor fees for most people, you can still deduct certain fees as an itemized deduction. The key one is interest expense—that is, if you borrowed money to make investments (known as “buying on margin”), you can deduct the interest you paid on that loan, up to the amount of your net investment income.
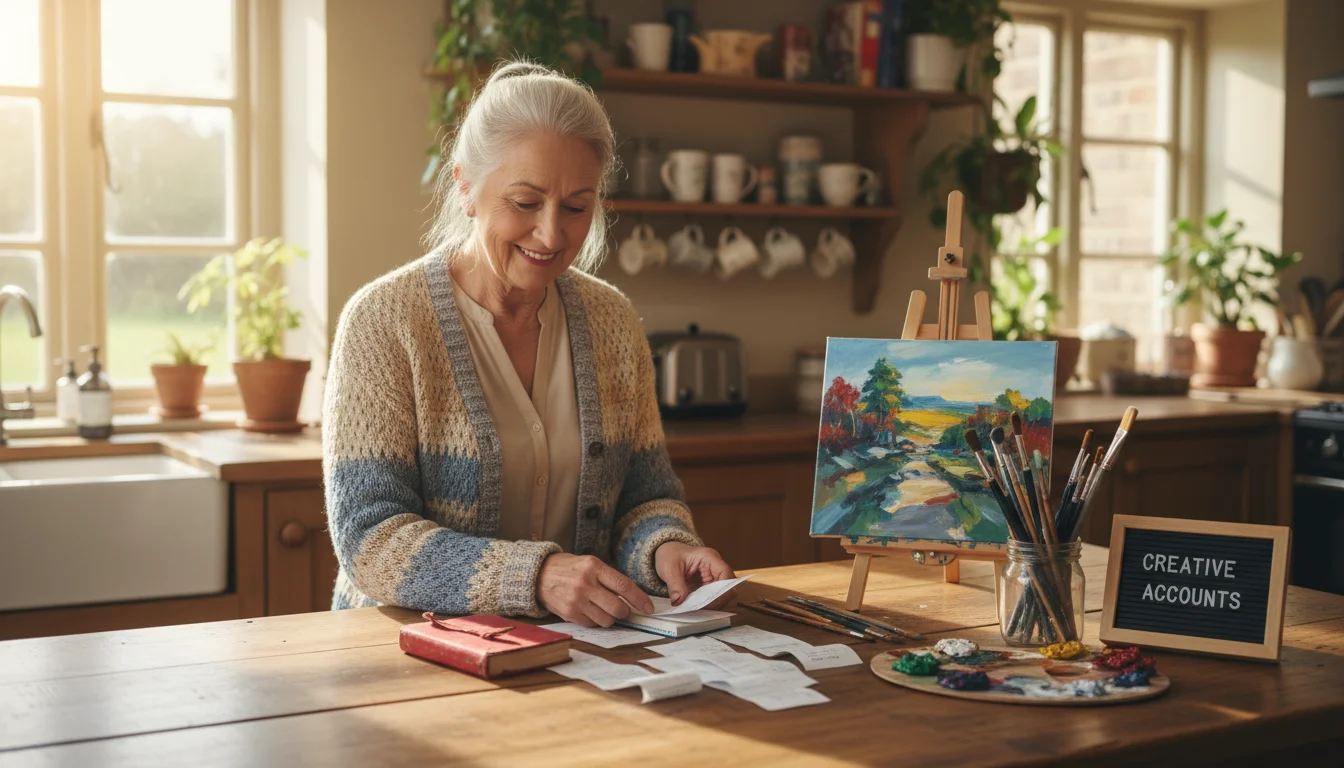
Older woman organizing receipts and a ledger at her kitchen table, with art supplies nearby.
Turning a passion into a purpose, and tracking those business expenses.

9. Business Expenses for a Side Hustle

Retirement is often a time to turn a hobby into a small business or do some consulting work. If you are self-employed, you can deduct ordinary and necessary business expenses. This can include a portion of your home expenses if you have a dedicated home office, supplies, mileage for business-related travel, and marketing costs.
Older Asian woman, late 60s, at kitchen table, holding a lottery ticket and using a calculator to tally numbers.
Tallying up the numbers after a little fun, making sure everything adds up.

10. Gambling Losses

This might seem surprising, but if you have winnings from gambling (casinos, lottery, etc.), you must report that as income. The silver lining is that you can also deduct your gambling losses as an itemized deduction, but only up to the amount of your winnings. You cannot deduct more than you won. So, if you won $1,000 during the year but lost $1,500, you can only deduct $1,000 of your losses, bringing your net taxable gambling income to zero.
Pages: 1 2 3 4 5 6

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • Pharmacist in a white coat hands a paper prescription bag to a customer over a counter with Medicare brochures. 10 Medicare Part D Details Worth Reading Twice
  • Senior couple walking arm in arm on a snowy brick sidewalk of a small town decorated with Christmas lights at dusk. 11 Small Cities With Free Holiday Events for Seniors
  • Senior woman with grey hair resting her head on her hand while sitting on a wooden garden bench outdoors. 10 Types of Fatigue That Need a Doctor's Look
  • Smiling senior couple sitting at an outdoor wooden table with a beer flight sampler and a ceramic mug outside a brewery. 11 Retirement Spots Known for Their Local Breweries and Cafes
  • Shoppers browse fresh vegetables, flowers, and ceramic mugs at a sunlit outdoor farmers market in a town square. 12 Retirement Towns Known for Their Farmers and Craft Markets
  • A man leans against a stone balustrade overlooking a hillside village, next to a table with coffee, a book, and keys. 12 Countries Where a U.S. Pension Buys a House Outright
  • A smiling senior woman in a blazer holds a portfolio while speaking with passengers on a cruise ship deck at sunset. 8 Part-Time Jobs at Retirement Cruise Lines for Seniors
  • Senior couple sitting at a wooden table reviewing medical receipts, expense logs, and calculating bills. 9 Tax Breaks Retirees Often Miss on Medical Expenses
  • Senior couple relaxing on a sunny porch, with a woman reading a newspaper in a wicker chair and a man holding a mug. 10 Things That Get Cheaper When You Move to a Smaller Town
  • A red backpack stands open on a wooden table beside a clear pouch organizing identity, insurance, and banking papers. 9 Financial Documents to Keep in an Emergency Go-Bag

Newsletter

Get the latest posts delivered to your inbox.

Related Articles

A sunlit living room with a framed close-up portrait of a smiling senior man on the mantelpiece, suggesting a secure and happy retirement.

Passive Income Streams Every Retiree Should Know

Actionable Strategies and Money-Saving Tips Now, let’s move from theory to practice. Here are some…

Read More →
An older couple sitting at a wooden table reviewing paperwork next to a calendar open to September and a steaming mug.

Why September Is the Most Important Month for Your 2027 COLA Calculation

Learn why September inflation data determines your 2027 Social Security COLA calculation and how the…

Read More →
An older woman with glasses on her head intently studies complex medical bills at a sunlit kitchen table, a magnifying glass and notebook nearby.

How to Negotiate Medical Bills After Retirement

How to Negotiate Medical Bills After Retirement As you navigate retirement on a fixed income,…

Read More →
An older man sitting at a sunlit kitchen table, calmly reviewing financial documents with a cup of tea, representing financial security.

7 Little-Known Senior Discounts That Can Save You Hundreds a Year

Discover little-known senior discounts on property taxes, utilities, auto insurance, and healthcare that can keep…

Read More →
A home office desk with a modern laptop and an old ledger, symbolizing the transition to new financial technology for seniors.

How to Leverage AI Tools to Manage Senior Finances

Table of Contents Introduction: Taking Control of Your Finances in Retirement Understanding the Financial Basics…

Read More →
A tablet on a patio table shows a video call with a smiling senior woman, with a green, sunlit garden in the background.

How to Choose the Right Health Insurance After Retirement

Actionable Strategies and Money-Saving Tips Choosing between these two paths is a personal decision that…

Read More →
An older woman smiles holding her smartphone next to a notepad on a sunlit kitchen table, feeling empowered.

The Telephone Consumer Protection Programs That Pay Seniors to Report Scam Calls

Learn how federal consumer protection programs allow seniors to claim $500 to $1,500 per illegal…

Read More →
An older couple sitting at a sunlit wooden kitchen table, calmly reviewing some papers together over coffee.

The Future of Social Security: What Experts Are Saying

Discover what the latest expert analysis and the 2026 Trustees Report mean for the future…

Read More →
A smiling senior woman sits at her desk in a bright home office, looking happy and in control of her finances.

How to Choose Between Annuities and Investments

Table of Contents Introduction: Taking Control of Your Finances in Retirement Understanding the Financial Basics…

Read More →
Helpful Resources for Seniors Helpful Resources for Seniors

Navigate life's next chapter with confidence

Inedit Agency S.R.L.
Bucharest, Romania

contact@helpfulresourcesforseniors.com

Explore

  • Home
  • About Us
  • Editorial Policy
  • Privacy Policy
  • Terms and Conditions
  • Subscribe
  • Unsubscribe
  • Contact
  • Request to Know
  • Request to Delete
  • CA Private Policy

Categories

  • Finance
  • Lifestyle
  • Well-Being

© 2026 Helpful Resources for Seniors. All rights reserved.